
Here is the Trading Markets article with new observations on life and markets. A reader astutely pointed out that it is talent *and* preparation that joins with opportunity to create success. Indeed.
As I'm writing, interest rates on the 10 year are dropping, the dollar is weakening vs. the Euro, and stocks are bouncing higher. Even on a short-term basis, these relationships are worth watching--particularly when the different markets are in sync and telling the same story.
Friday, March 31, 2006
Thursday, March 30, 2006
Interest Rates Up; Financial Stocks Down
In the last four trading sessions, interest rates on the 10-year note ($TNX) have risen by about 3.85%, while financial stocks ($BKX) have been down -1.65%. What happens after we have such rising rates and weakening financial issues?
I went back to January, 2003 (N = 813) and found 99 occasions in which interest rates had risen by 3% or more in a four-day period. Four days later, interest rates rose on average another .58% (55 up, 44 down). When interest rates were up by 3% and $BKX was down more than 1% over the four-day period (N = 25), rates rose over the next four days by an average .71% (16 up, 9 down).
Interestingly, this pattern appears to have changed over the course of the lookback period. When I examined the most recent data in which interest rates were up and $BKX was down (N = 13), the next four-day rise in rates was only .12%, but the next four day change in SPY was down -.20% (6 up, 7 down). This is weaker than the average four-day gain in SPY of .18% (457 up, 356 down).
When I looked at the data in 2003 and early 2004 (N = 12), the next four-day rise in rates was 1.36%, but the average four-day change in SPY was .42% (7 up, 5 down). Early in the bull market, rate rises led to greater rate rises, but also led to stock strength. More recently, rate rises have not led to greater rate rises, but have led to stock underperformance in the near term.
Whereas stocks held their ground during interest rate rises early in the bull market, they now display subnormal returns. That appears to be particularly the case among financial and large cap issues.
I went back to January, 2003 (N = 813) and found 99 occasions in which interest rates had risen by 3% or more in a four-day period. Four days later, interest rates rose on average another .58% (55 up, 44 down). When interest rates were up by 3% and $BKX was down more than 1% over the four-day period (N = 25), rates rose over the next four days by an average .71% (16 up, 9 down).
Interestingly, this pattern appears to have changed over the course of the lookback period. When I examined the most recent data in which interest rates were up and $BKX was down (N = 13), the next four-day rise in rates was only .12%, but the next four day change in SPY was down -.20% (6 up, 7 down). This is weaker than the average four-day gain in SPY of .18% (457 up, 356 down).
When I looked at the data in 2003 and early 2004 (N = 12), the next four-day rise in rates was 1.36%, but the average four-day change in SPY was .42% (7 up, 5 down). Early in the bull market, rate rises led to greater rate rises, but also led to stock strength. More recently, rate rises have not led to greater rate rises, but have led to stock underperformance in the near term.
Whereas stocks held their ground during interest rate rises early in the bull market, they now display subnormal returns. That appears to be particularly the case among financial and large cap issues.


A Dozen Reflections on Life and Markets
***
Note: When I returned from vacation, I found that this article, written about two years ago, had been downloaded over 60,000 times in three days. Such are the viral ways of the Web. A followup reflections article will appear on the Trading Markets site tomorrow.
***
I've never seen a trader succeed whose explicit or implicit goal was to not lose. The trader who trades to not lose is like the person who lives to avoid death: both become spiritual hypochondriacs.
No union was ever destroyed by a failure of romance. It is the loss of respect, not love, which ends a relationship.
Love, once present, never dies. It must be killed.
Sometimes we select markets--and trading styles--much as we choose romantic partners: by their ability to validate our deepest-held images of ourselves. Our choices generally succeed, for better or for worse.
Many a trader fears boredom more than loss, thereby experiencing the two in sequence.
Goodness of character is measured in loyalty to others; greatness of character is measured in loyalty to principle.
A measure of the soul: the degree to which the surpassing achievements of others evoke inspiration rather than envy.
If you listen to the words, you'll understand the brains of the speaker. If you listen to the tone, you'll understand his heart.
Show me what a man loathes, and I will show you what he cannot accept in himself.
Two traders: one increases size after a loss; the other gets smaller. Both continue to lose.
One encounters losing traders as often as one encounters losing golfers--and for much the same reason.
The absence of self-acceptance too often masquerades as the desire for self-improvement.
Wednesday, March 29, 2006
Trading Update 3/29
Regular updates on the Trading Psychology Weblog will resume Thursday evening; also on Thursday, the historical pattern analyses will resume here on the TraderFeed site.
Wednesday's market was strong out of the gate, with NASDAQ and small cap issues leading the way. There was very solid buying across the market, as we vaulted to the highs of the recent range in the S&P, but went to new recent highs in the broad indices. This places us in a short term uptrending mode. Even in the face of higher interest rates, it appears that selloffs are bringing in buyers. Demand expanded greatly to 122; Supply was 41. New 20 and 65 day highs expanded to 1308 and 787; new 20 and 65 day lows were 610 and 254. Normally such upside momentum as we're seeing in the Demand/Supply numbers carries over in the short-term.
Wednesday's market was strong out of the gate, with NASDAQ and small cap issues leading the way. There was very solid buying across the market, as we vaulted to the highs of the recent range in the S&P, but went to new recent highs in the broad indices. This places us in a short term uptrending mode. Even in the face of higher interest rates, it appears that selloffs are bringing in buyers. Demand expanded greatly to 122; Supply was 41. New 20 and 65 day highs expanded to 1308 and 787; new 20 and 65 day lows were 610 and 254. Normally such upside momentum as we're seeing in the Demand/Supply numbers carries over in the short-term.
Tuesday, March 28, 2006
Trading Update 3/28
First interest rates moved higher on strong economic news, then stocks sold off in response to Fed tightening. The result is that we moved well below the recent multiday range, setting off a short-term downtrend. It was a good example of a dynamic discussed recently, in which moves in the stocks are most likely to trend when we see significant movements in energy, interest rates, and or currencies. New 20 and 65 day lows expanded to 618 and 234; Supply exceed Demand by 101 to 48. As long as we continue to make day over day lows and expand new lows and Supply, selling bounces below the day's average price is the operative mode.
Monday, March 27, 2006
Trading Update Monday 3/27
I'll be returning to regular blog posts and updates on the Trading Psychology Weblog on Thursday. Monday's market continued the narrow action in the S&P 500, continuing the neutral trend. It was a great illustration of the kind of day I referenced in the recent post about mean reversion. Knowing the day's average price and seeing: a) an open near the average price; and b) low volatility from the prior session; and c) modest early volume allowed traders to lean on the market's tendency to revert to that average price. Here is the Trading Markets article on that topic.
I notice that we had an expansion of new 20 and 65 day highs, but also an expansion of lows. Demand was 59; Supply was 69, which means we had slightly more stocks showing negative momentum than positive--but the majority not showing any distinct momentum. We need to see a move out of the recent several day range accompanied by an expansion of new highs/lows to establish a directional trend.
I notice that we had an expansion of new 20 and 65 day highs, but also an expansion of lows. Demand was 59; Supply was 69, which means we had slightly more stocks showing negative momentum than positive--but the majority not showing any distinct momentum. We need to see a move out of the recent several day range accompanied by an expansion of new highs/lows to establish a directional trend.
Sunday, March 26, 2006
Mean Reversion: How Often Does It Occur?

Recent posts have looked at the market's lack of trending and, indeed, its tendency to reverse moves. Does this suggest that the market tends to revert to mean trading prices? If so, might we find tradable strategies from this tendency?
I went back to March, 2003 (N = 773) and investigated each day of performance in the Dow Jones Industrial Average (DIA). I computed the previous day's average price simply as the average of the open-high-low-close. I then looked to see how often this average price was touched during the following day's trade.
It turns out that we revert to this mean trading price approximately 63% of the time. Since February of this year, that proportion has risen to over 70%. Are there variables that predict an even greater occurrence of this reversion? Do we see different levels of reversion on different time frames? Lots of good research questions here. Stay tuned.
Saturday, March 25, 2006
Countertrend Equivalence - An Intermediate-Term Look

My recent Trading Markets article, along with recent blog entries here, found evidence of countertrend equivalence on a 5 day basis and, to a more modest degree, over a 5 hour timeframe. Recall that the idea of countertrend equivalence is that, if the market establishes a strong trend over X period, the next X period will tend to reverse this trend.
I decided to extend the analysis by looking at 5 week periods in SPY. Since March, 2003 (N = 155) we have had 27 strong uptrending periods on my trend measure. Five weeks later, SPY averaged a gain of .67% (16 up, 11 down), weaker than the average five-week gain of 1.36% (103 up, 52 down).
To create a relative match, I looked at the 25 strongest downtrending periods in SPY during that same time. Five weeks later, SPY averaged a gain of 2.36% (18 up, 7 down)--much stronger than normal.
Once again, we see evidence of countertrending, with moves over one period reversed in the next. The effect is especially strong for reversals of downtrends on a five day and five week basis, suggesting that these timeframes might be worth coordinating for intermediate-term trades.
Friday, March 24, 2006
Observations on Trading Fundamentals and Risk Management
One of the interesting aspects of writing my current book on trader performance is interviewing people who have long years of experience as traders and as mentors to traders. To a person, they emphasize that success in trading is not a function of finding better indicators or trading patterns. Rather, they emphasize the seemingly mundane aspects of trading mechanics: sticking to trading plans, managing risk, and adapting to changing market conditions.
While the historical patterns on this site are useful food for thought and a worthwhile starting point for framing market understandings--and trade ideas, they cannot substitute for the fundamentals emphasized by these mentors.
Of these, risk management is perhaps the most important. Victor Niederhoffer, in his excellent book The Education of a Speculator, uses the example of trying to make $10.00 from $1.00 when you have a 60/40 chance of winning a dollar from each individual bet. The odds of ruin in such a game are about 66%. Indeed, one would need a bankroll in excess of $4.00 to make the pursuit of $10.00 a worthwhile game--even with 60/40 odds.
The moral of the story is that good odds aren't enough. Proper position sizing--and a bankroll sufficient to weather the inevitable strings of losses that occur with chance--are all-important. I have seen more psychological problems created by poor money management than the reverse. Losses should not be traumatic--emotionally or financially--if they are built into the trading plan and kept to a very reasonable fixed fraction of portfolio size.
While the historical patterns on this site are useful food for thought and a worthwhile starting point for framing market understandings--and trade ideas, they cannot substitute for the fundamentals emphasized by these mentors.
Of these, risk management is perhaps the most important. Victor Niederhoffer, in his excellent book The Education of a Speculator, uses the example of trying to make $10.00 from $1.00 when you have a 60/40 chance of winning a dollar from each individual bet. The odds of ruin in such a game are about 66%. Indeed, one would need a bankroll in excess of $4.00 to make the pursuit of $10.00 a worthwhile game--even with 60/40 odds.
The moral of the story is that good odds aren't enough. Proper position sizing--and a bankroll sufficient to weather the inevitable strings of losses that occur with chance--are all-important. I have seen more psychological problems created by poor money management than the reverse. Losses should not be traumatic--emotionally or financially--if they are built into the trading plan and kept to a very reasonable fixed fraction of portfolio size.
Thursday, March 23, 2006
Short-Term Countertrend Equivalence

My last post introduced the idea of countertrend equivalence: Once we get a solid trend reading for a period of time X, the next period X tends to reverse this trend. We saw that this occurred over a five-day period: if we have a strong trend over five days in SPY, the next five days tend to run counter to this trend.
I took a look at hourly SPY data going back to 11/21/05 (N = 586). When we've had a strong uptrend over a five hour period (N = 75), the next five hours in SPY average a loss of -.08% (33 up, 42 down). That is weaker than the average five-hour gain of .04% (312 up, 274 down) for the general sample.
When we've had a strong downtrend over a five-hour period (N = 47), the next five hours in SPY have averaged a gain of .18% (29 up, 18 down). This is noticeably stronger than the sample overall.
Once again, we see evidence of countertrend equivalence. I will pursue this topic further in my upcoming Trading Markets article.
Countertrend Equivalence: An Interesting Idea
I'm following up on the broad market's countertrend tendencies. When my trend measure registers that the market is trending over X time periods, it appears that the next X periods tend to reverse this trend. I need to research this further but, if true, this countertrend equivalence could be a solid basis for combining time frames in analysis. In other words, let's say you had a strong downtrend reading on an intraday basis *and* on a multiday basis. That should provide an excellent signal for a longer-term market purchase.
I went back to March, 2003 (N = 766) and examined five-day trend readings in SPY and then what happened in the *next* five days of SPY trading. When SPY displayed a strong five-day downtrend (N = 104), the next five days in SPY averaged a gain of .80% (68 up, 36 down). That is much stronger than the average five-day gain of .31% (448 up, 318 down) for the overall sample.
When SPY displayed a strong five-day uptrend (N = 196), the next five days in SPY averaged a gain of .17% (108 up, 88 down), weaker than the average five-day gain for the broad sample.
In short, five day trends are tending to reverse. The next question is: can we pair these five day periods with other time frames to create superior timing of trades?
I went back to March, 2003 (N = 766) and examined five-day trend readings in SPY and then what happened in the *next* five days of SPY trading. When SPY displayed a strong five-day downtrend (N = 104), the next five days in SPY averaged a gain of .80% (68 up, 36 down). That is much stronger than the average five-day gain of .31% (448 up, 318 down) for the overall sample.
When SPY displayed a strong five-day uptrend (N = 196), the next five days in SPY averaged a gain of .17% (108 up, 88 down), weaker than the average five-day gain for the broad sample.
In short, five day trends are tending to reverse. The next question is: can we pair these five day periods with other time frames to create superior timing of trades?
Wednesday, March 22, 2006
Coming Market Research
Just wanted to outline a direction my research will be taking, integrating the theme from the last post (looking at multiple time frames) and the recent theme of market trending. I'll be working on creating trending measures of the markets on two different time frames and then will see if combining short- and longer-term trend measures helps us identify historical patterns. If so, that would be significant, because the trend measures will be ones that could be applied to any stocks or markets.
A second direction is identifying sectors that commonly lead the broad market and comparing their trend measures with that of the broad market. My hypothesis is that a "crossover", in which the trend of the leading market overtakes the broad market trend, might provide an entry signal for short-term trend followers.
Thanks again to readers who continue to provide lots of good food for thought. I hope this blog returns those favors--
Brett
A second direction is identifying sectors that commonly lead the broad market and comparing their trend measures with that of the broad market. My hypothesis is that a "crossover", in which the trend of the leading market overtakes the broad market trend, might provide an entry signal for short-term trend followers.
Thanks again to readers who continue to provide lots of good food for thought. I hope this blog returns those favors--
Brett
What's Happening on the Larger Time Frame: Does It Matter?
A reader recently made the valuable point that, in addition to looking at such key aspects of the market as volatility, momentum, trend, and sentiment, it is necessary to look across different time frames. That raises an interesting question: Do time frames matter? If we see a historical pattern on one time frame, does what's happening on the larger time frame make a difference?
To address this issue, I looked at yesterday's market, in which SPY was down -.63%. Going back to March, 2003 (N = 765), I found 95 occurrences in which SPY was down between half a percent and a full percent. The next two days in SPY averaged a gain of .20% (55 up, 40 down), stronger than the average two-day gain in the SPY sample of .12%.
I then divided the same down day sample of SPY into two categories based on time frame performance. One group was down between half and a full percent and was making a five-day closing low (just like yesterday; N = 46). The other group was down by the same amount but not making a five-day closing low (N = 49).
When the down day in SPY was making a five-day low, the next two days in SPY averaged a gain of .40% (29 up, 17 down). When the down day in SPY was not making a five-day low, the next two days in SPY averaged a flat performance (26 up, 23 down). Thus, the bullish implications of a down SPY day are entirely attributable to the fact that they're five-day lows. The larger time frame matters quite a bit.
This is a moderately bullish consideration for today, especially if early action fails to take the averages below yesterday's lows. Hats off to the reader for an excellent observation.
To address this issue, I looked at yesterday's market, in which SPY was down -.63%. Going back to March, 2003 (N = 765), I found 95 occurrences in which SPY was down between half a percent and a full percent. The next two days in SPY averaged a gain of .20% (55 up, 40 down), stronger than the average two-day gain in the SPY sample of .12%.
I then divided the same down day sample of SPY into two categories based on time frame performance. One group was down between half and a full percent and was making a five-day closing low (just like yesterday; N = 46). The other group was down by the same amount but not making a five-day closing low (N = 49).
When the down day in SPY was making a five-day low, the next two days in SPY averaged a gain of .40% (29 up, 17 down). When the down day in SPY was not making a five-day low, the next two days in SPY averaged a flat performance (26 up, 23 down). Thus, the bullish implications of a down SPY day are entirely attributable to the fact that they're five-day lows. The larger time frame matters quite a bit.
This is a moderately bullish consideration for today, especially if early action fails to take the averages below yesterday's lows. Hats off to the reader for an excellent observation.
Tuesday, March 21, 2006
The Power Measure: What Happens Once a Trend Emerges?
Yesterday's entry on the Trading Psychology Weblog dusted off a proprietary indicator I developed a while ago, which I dubbed the Power Measure. It was my very first effort to measure a variable I call "trendiness": the market's tendency to persist in directional movement. After writing the recent articles that tracked the decreasing trendiness of the stock indices, I decided to modify the Power Measure and utilize it as an operational measure of trending that could be applied to a variety of markets and time frames. The nice thing about the measure is that it creates a normalized measurement, in which perfect upward trending earns a score of +100 and perfect downward trending earns a score of -100. Scores near zero suggest absence of trending: a tendency for price movement in period one to reverse in period two. Note that the Power Measure is a pure measure of price persistence; it does not confuse momentum/price strength with trending.
I went back to March, 2003 (N = 759) and looked at future price movement in SPY as a function of the Power Measure reading. When the measure was 90 or greater (consistent upside trending; N = 85), the next three days in SPY averaged a loss of -.02% (43 up, 42 down)--much weaker than the average three-day gain of .18% for the sample overall (443 up, 316 down).
When the Power Measure was -80 or lower (consistent downside trending; N = 55), the next three days in SPY averaged a gain of .53% (39 up, 16 down)--much stronger than average.
This is the clearest cut evidence I've yet seen of a countertrend bias to the market. Waiting for a distinct trend to emerge and then fading it has proven far more successful as a trading strategy than trying to ride trends. It will be interesting to see if this holds for shorter time frames as well. If my future investigations prove equally promising, I'll bring the Power Measure back to the Weblog.
I went back to March, 2003 (N = 759) and looked at future price movement in SPY as a function of the Power Measure reading. When the measure was 90 or greater (consistent upside trending; N = 85), the next three days in SPY averaged a loss of -.02% (43 up, 42 down)--much weaker than the average three-day gain of .18% for the sample overall (443 up, 316 down).
When the Power Measure was -80 or lower (consistent downside trending; N = 55), the next three days in SPY averaged a gain of .53% (39 up, 16 down)--much stronger than average.
This is the clearest cut evidence I've yet seen of a countertrend bias to the market. Waiting for a distinct trend to emerge and then fading it has proven far more successful as a trading strategy than trying to ride trends. It will be interesting to see if this holds for shorter time frames as well. If my future investigations prove equally promising, I'll bring the Power Measure back to the Weblog.
Monday, March 20, 2006
Small and Midcap Stocks: Relative Performance and What It Means
My recent Trading Markets article took a look at how small cap performance acts as a mediator of past and future S&P performance, creating a statistical interaction effect. Today we had an interesting situation in which the S&P Midcaps ($MID) underperformed the S&P Small Caps ($SML). Specifically, SML was up .03% and MID was down -.34%.
Going back to March, 2003 (N = 766), I found 127 occasions in which the day's change in SML was within plus or minus .20%. The next day in SPY averaged .01% (63 up, 64 down), which is weaker than next day results for the sample overall. Once again, however, we see an interaction effect. When SML is neutral and MID is strong, the next day in SPY averages a loss of -.11 (29 up, 35 down). When SML is neutral and MID is weak, the next day in SPY averages a gain of .13% (34 up, 29 down).
Once again we see that a critical mediating effect is played by the relative outperformance or underperformance of the small cap stocks. When SML is neutral but outperforms MID, next day results in SPY are more favorable than when SML is neutral but underperforms MID. Score this as a mild bullish consideration for tomorrow.
Going back to March, 2003 (N = 766), I found 127 occasions in which the day's change in SML was within plus or minus .20%. The next day in SPY averaged .01% (63 up, 64 down), which is weaker than next day results for the sample overall. Once again, however, we see an interaction effect. When SML is neutral and MID is strong, the next day in SPY averages a loss of -.11 (29 up, 35 down). When SML is neutral and MID is weak, the next day in SPY averages a gain of .13% (34 up, 29 down).
Once again we see that a critical mediating effect is played by the relative outperformance or underperformance of the small cap stocks. When SML is neutral but outperforms MID, next day results in SPY are more favorable than when SML is neutral but underperforms MID. Score this as a mild bullish consideration for tomorrow.
Sunday, March 19, 2006
Large Caps Strong, Small Caps Stronger: What Next?
We've had a strong six-day run in the large cap stocks, with XMI up over 2.5% in that period. Small cap issues (SML) have been even stronger, up about 4%. I decided to look at what happens in the S&P 500 (SPY) since March, 2003 (N = 762) after a big cap run and whether small caps play a role in future performance.
I found 94 occasions of six-day XMI gains of over 2%. Six days later, SPY was up by an average of .17% (55 up, 39 down), which is less than the average six-day gain for the sample of .37% (449 up, 313 down). When XMI was up by more than 2% in six days and SML was strong (N = 47), the next six days in SPY averaged .50% (31 up, 16 down). When XMI was similarly up and SML was weak (N = 47), the next six days in SPY averaged a loss of -.16% (24 up, 23 down).
Once again, it appears that performance in the small caps mediates future performance in the S&P 500--this time on a longer time frame. When the large caps are strong and small stocks are relatively weak, the S&P noticeably underperforms over the next six days. When the large caps are strong and small stocks are also strong, there are greater odds of continuation of strength. We'd have to chalk this one up as moderately favorable for the bulls.
I found 94 occasions of six-day XMI gains of over 2%. Six days later, SPY was up by an average of .17% (55 up, 39 down), which is less than the average six-day gain for the sample of .37% (449 up, 313 down). When XMI was up by more than 2% in six days and SML was strong (N = 47), the next six days in SPY averaged .50% (31 up, 16 down). When XMI was similarly up and SML was weak (N = 47), the next six days in SPY averaged a loss of -.16% (24 up, 23 down).
Once again, it appears that performance in the small caps mediates future performance in the S&P 500--this time on a longer time frame. When the large caps are strong and small stocks are relatively weak, the S&P noticeably underperforms over the next six days. When the large caps are strong and small stocks are also strong, there are greater odds of continuation of strength. We'd have to chalk this one up as moderately favorable for the bulls.
Saturday, March 18, 2006
Small vs. Large Cap Performance: Impact on Next Day Trading
Here's a look at a relatively pure measure of large cap performance, the Major Market Index ($XMI), vs. a relatively pure measure of small cap performance, the S&P 600 ($SML). On Friday, we barely moved on XMI, registering a loss of -.07%. SML was stronger, rising .26%.
I decided to go back to March, 2003 (N = 765) and see how next day performance in the S&P 500 was impacted by previous relative performance in SML vs. XMI. I found 192 occasions in which XMI closed with a gain of less than .20% and a loss not greater than -.20%. The average next day performance in SPY was .07% (107 up, 85 down).
On narrow XMI days in which SML was strong (N = 96), the average next day gain was .10% (58 up, 38 down). On narrow XMI days in which SML was weak, the average next day gain was only .04% (49 up, 47 down). This is a pattern I have noticed before: smaller cap performance appears to lead that in larger caps. As long as SML outperforms XMI, short-term returns tend to be more favorable than when SML underperforms. I'll be taking further looks at these sectors in the near future.
I decided to go back to March, 2003 (N = 765) and see how next day performance in the S&P 500 was impacted by previous relative performance in SML vs. XMI. I found 192 occasions in which XMI closed with a gain of less than .20% and a loss not greater than -.20%. The average next day performance in SPY was .07% (107 up, 85 down).
On narrow XMI days in which SML was strong (N = 96), the average next day gain was .10% (58 up, 38 down). On narrow XMI days in which SML was weak, the average next day gain was only .04% (49 up, 47 down). This is a pattern I have noticed before: smaller cap performance appears to lead that in larger caps. As long as SML outperforms XMI, short-term returns tend to be more favorable than when SML underperforms. I'll be taking further looks at these sectors in the near future.
Friday, March 17, 2006
Closing NYSE TICK: Does It Matter?
Here is the Trading Markets article on Euro currency trading; thanks for the interesting comments.
I decided to take a look at the closing level of the NYSE TICK and whether it has any relevance for the next day's trading. Friday we closed above +900 on the TICK, suggesting broad buying on the close. Indeed, the final TICK number might be viewed as the leaning of traders' market-on-close positions, as they either lift offers or hit bids in stocks.
My first observation, going back to March, 2003 (N = 767), is that there is a positive bias to the data. The average closing TICK value is 452.
When the TICK closes above 900 (N = 82), the next day in the S&P 500 (SPY) averages a gain of .11% (48 up, 34 down). This is stronger than the average gain for the sample of .06% (429 up, 339 down).
When the TICK closes below -200 (N = 43), the next day in the S&P 500 averages a gain of .26% (28 up, 15 down). It thus appears that selling on the close tends to reverse the following day, while strong buying on the close has a moderate tendency to continue the next day.
Combining the closing TICK with momentum measures, such as the Demand/Supply Index, might screen for particularly positive times to buy the market. Another idea would be to track the TICK readings from the final hour of trade and the impact the next day.
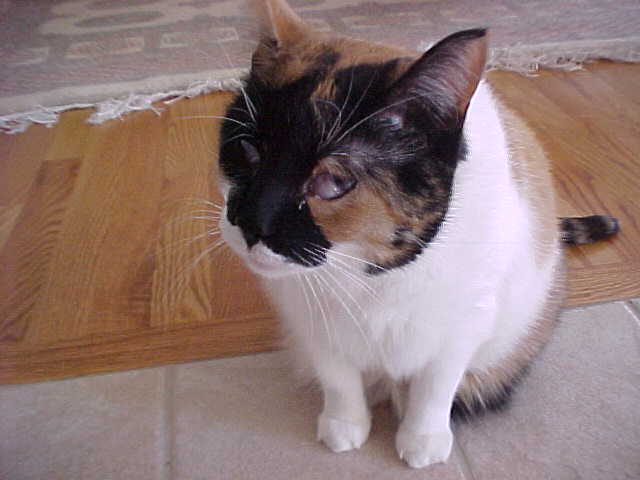
PS - Above is Mali, the blind cat we adopted in Syracuse. When we moved to Naperville to a three story house, Mali took a day and a half to find her way around completely. That was before we got our furniture in. She adapted to the furniture in a day. She constantly sniffs as she moves, and her hearing is excellent. She comes running whenever she hears someone visiting us--she loves meeting new people. How many of our senses do we engage in trading, and how much information processing do we lose by being solely dependent upon sight?
Thursday, March 16, 2006
Forex: Know the Market You're Trading!
My recent article in Trading Markets emphasized the importance of the fit between the personality of a market--its degree of volatility and trending--and the trading style of the trader. Quite a few readers wrote to me, asking about which market would be best for them. Many asked specifically about currency (forex) trading, since instruments such as the Euro are known to be trending and volatile.
My next article for Trading Markets will examine whether the Euro truly is a superior trading instrument. I think you'll be surprised by the findings. Without giving away too many punch lines here, allow me to mention one important finding: I find no evidence of trending in the currency market on either a 30 minute or daily basis. In fact, up periods are modestly more likely to be followed by down periods (and vice versa) than by continuation.
Many brokerage houses specializing in currency trading--especially those going after retail customers--stress what wonderful trending markets currencies are. They also emphasize commission-free trading with "only" a three-pip spread and possible leverage of several hundred to one on your money.
Well, each pip in the Euro emini is like a tick in the S&P emini: worth $12.50. So the highly leveraged trader in a market he thinks is trending, buys a volatile period and what happens? He is down three ticks on size already even if he scratches the trade. But when the market reverses with high volatility, he quickly is in the red by a substantial amount.
I spoke with a very well placed industry insider who revealed to me that the average length of time from the opening of a trading account to the closing of that account was seven months. This was not because the trader was dissatisfied with the firm; rather, that was how long it took the average customer to blow through their capital.
Yale Hirsch says, "Investigate before you invest." That's wisdom that applies equally to traders.
My next article for Trading Markets will examine whether the Euro truly is a superior trading instrument. I think you'll be surprised by the findings. Without giving away too many punch lines here, allow me to mention one important finding: I find no evidence of trending in the currency market on either a 30 minute or daily basis. In fact, up periods are modestly more likely to be followed by down periods (and vice versa) than by continuation.
Many brokerage houses specializing in currency trading--especially those going after retail customers--stress what wonderful trending markets currencies are. They also emphasize commission-free trading with "only" a three-pip spread and possible leverage of several hundred to one on your money.
Well, each pip in the Euro emini is like a tick in the S&P emini: worth $12.50. So the highly leveraged trader in a market he thinks is trending, buys a volatile period and what happens? He is down three ticks on size already even if he scratches the trade. But when the market reverses with high volatility, he quickly is in the red by a substantial amount.
I spoke with a very well placed industry insider who revealed to me that the average length of time from the opening of a trading account to the closing of that account was seven months. This was not because the trader was dissatisfied with the firm; rather, that was how long it took the average customer to blow through their capital.
Yale Hirsch says, "Investigate before you invest." That's wisdom that applies equally to traders.
Wednesday, March 15, 2006
Strong NASDAQ, Low TRIN: Short-Term Results
First off, I want to thank readers who have suggested ideas for research and who have provided helpful feedback re: this and the Trading Psychology sites. Thanks also to readers who have shown interest in The Psychology of Trading; for it to have cracked the top 10,000 on Amazon three years after its publication is a testament to the enduring relevance of psychology for trading. My new book, Enhancing Trader Performance, is undergoing editing and should be published this fall.
A reader very helpfully pointed out that strong gains accompanied by low TRIN readings are bullish on a next day basis. Recall that my analysis yesterday showed weakness over the intermediate term. Fortunately today provided an opportunity to test the reader's idea: We have closed higher by 2.56% on the NASDAQ 100 ETF (QQQQ) over the past two days. The NASDAQ TRIN during that time has averaged .496.
Going back to March, 2003 (N = 762), I found 81 instances of a two-day rise of more than 2% in QQQQ. Over the next two days, QQQQ was higher by an average .26% (50 up, 31 down), stronger than the average two-day rise of .15% (413 up, 349 down) for the broad sample. When, however, QQQQ was up by more than 2% on a two-day basis and the TRIN averaged less than .50 over that same time (N = 20), the next two days were up by an average of .54% (13 up, 7 down). Score one for short-term bulls and for an astute reader.
A reader very helpfully pointed out that strong gains accompanied by low TRIN readings are bullish on a next day basis. Recall that my analysis yesterday showed weakness over the intermediate term. Fortunately today provided an opportunity to test the reader's idea: We have closed higher by 2.56% on the NASDAQ 100 ETF (QQQQ) over the past two days. The NASDAQ TRIN during that time has averaged .496.
Going back to March, 2003 (N = 762), I found 81 instances of a two-day rise of more than 2% in QQQQ. Over the next two days, QQQQ was higher by an average .26% (50 up, 31 down), stronger than the average two-day rise of .15% (413 up, 349 down) for the broad sample. When, however, QQQQ was up by more than 2% on a two-day basis and the TRIN averaged less than .50 over that same time (N = 20), the next two days were up by an average of .54% (13 up, 7 down). Score one for short-term bulls and for an astute reader.
Subscribe to:
Posts (Atom)

 Posts


