
This is an important blog entry; you may want to review the posting from 2/26 (Sequence Analysis) before reading what I have here. The following is an example of sequence analysis at work.
Let's set the stage. After an up day on Monday which made a five-day high, we sold off on Tuesday and made a five-day low. Several of my analyses suggested a high likelihood of a down day today.
In sequence analysis, you always update forecasts with the most recently available data. This morning, the market opened up by more than a quarter of a percent. The updated forecast thus asked the question: What has happened historically when a down day has been followed by an up open? Specifically, I looked at occasions in which the market was down more than .75% on the day (N = 118) since March, 2003 (N = 755) and then divided the sample in half based on the following day's open.
When the next day's open is strong (as was the case today; N = 59), the average move from the open to the close has been .19% (38 up, 21 down). When the next day's open is weak (N = 59), the average move from the open to the close has been -.01% (33 up, 26 down).
Looking a bit further out, when the market opens strong after the down day, the move to the *following day's* close has been .41% (36 up, 23 down). When the market opens weak after the down day, the move to the *following day's* close has been -.06% (29 up, 30 down).
In short, a strong open following a weak day affects the market's short-term trajectory. This is an example of how updating forecasts with real time data can greatly aid trading. Traders need not wait for real time events to occur, however, to conduct these analyses. They can prepare for real time possibilities by conducting "what-if" scenarios with the historical data. Such sequence analysis would look at all historical occasions of market declines such as Tuesday's and then investigate what happened when the following day opened strong.
This captures the difference between mechanical system traders and historical pattern traders. Mechanical traders trade a model. Historical pattern traders conduct ongoing modeling as a dynamic process. Very, very few traders understand this and appreciate its potential.
Wednesday, March 01, 2006
Tuesday, February 28, 2006
Five Day High...Then Five Day Low

Yesterday we closed at a five-day high in SPY; today we closed at a five-day low. That's quite a reversal. I decided to consult the historical record and see what tends to happen next.
Perhaps the main finding is that this is a rare occurrence. I found only 9 such instances since January, 2003 (N = 790). That means that we need to take any analysis with multiple grains of salt.
Two days after the market made its five-day low (after having just made a five-day high), SPY was down by an average .17% (3 up, 6 down). That's quite a bit worse than the average two-day gain of .09% for the sample overall.
I have yet to compile my Demand/Supply numbers, but if they're as negative as I expect, that too would bode poorly for the bulls in the short run. Keep an eye on the Trading Psychology Weblog later tonight, and I'll have those numbers posted along with a brief analysis.


Monday, February 27, 2006
A New Look at Weak Energy Stocks and the S&P 500

For those who have requested the link, here is the article on first hour patterns in trading.
The relationship between the energy sector and the broad market indexes is a bit complicated. On one hand, you'd expect falling energy prices to benefit the economy and stocks. On the other hand, energy issues are well weighted within the major averages. For instance, since March, 2003 (N = 746), I find the correlation between the S&P 500 Index (SPY) and the energy ETF (XLE) to be .42. While this is significantly positive, it is lower than the correlations we see between many sectors and SPY.
We currently have an interesting situation in which SPY is up over the last four days by a little over three quarters of a percent, but XLE is down about 2.5%. Because such a move in different directions is relatively rare, I decided to take a historical look at what typically happens afterward.
Since March, 2003 (N = 746), we have had 111 occasions in which XLE has been down by more than 2% over a four-day period. Over the next four days, SPY has averaged a gain of .53% (72 up, 39 down). This is considerably stronger than the average four-day gain of .20% (359 up, 276 down) for the remainder of the sample.
Even more strikingly, we've had 32 days in which XLE has been down by 2% or more and SPY has been up over that period. Four days later, the average gain in SPY has been .83% (22 up, 11 down). This strength carries over to eight days out, with SPY up by an average 1.62% (27 up, 6 down). That is quite an edge.
It thus appears that strength in the S&P at a time of falling energy stock prices is bullish 1-2 weeks out. We'll count this one for the bulls going forward.
Sunday, February 26, 2006
Sequence Analysis and Lean Processes in Trading

On the Trader Performance blog, I recently posted an entry that looks at the process of defining and managing trade ideas from the perspective of lean manufacturing. One of the things I'm finding is that it is less difficult than I thought to identify trades that have a meaningful directional edge. If you have a good set of predictive measures, employ them properly over a truly representative lookback period, and then ensure that the relationships you identify apply to the entire lookback period, you can define an edge. The problem is managing this edge.
Let's say, apropos of my last analysis, that you find that a trade has a significant positive directional bias over the next ten days, with many more winning trades than losers. The question then becomes, over the next ten days, how do you determine whether or not the trade continues to possess its favorable edge? Suppose the market drops during the first two days of the trade period: do you continue to hold, add to the position, or exit? This is partly a question of risk management, but also a question of odds. If the two-day dip actually increases the odds of the trade going your way, exiting in the name of risk management seems perverse. It would be far better to start out with a position size that allows you to weather such adverse movement.
What I'm currently working on is something I call "sequence analysis". I examine every historical trade identified in my analyses and then walk them forward to identify the normal sequences of profits and losses. I'm specifically looking for key events that separate the winning trades from the losers, so that these could serve as rational exit points. To give but one simple example, if I find that 85% of all winning 10-day trades started out by being profitable in the first two days, I might not want to hold a loser after two days.
Sequence analysis becomes much more interesting and complex when you utilize predictors not in the original analysis to evaluate the likelihood that a historical pattern will repeat itself. For example, I might forecast a favorable ES over the next ten days based on the relative movements of Speculative and Non-Speculative stocks. My sequence analysis, however, may reveal that the vast majority of profitable trades occurred when the Adjusted TICK was positive in the first day of the 10-day period. That provides me with a tool for managing the trade. Do I really want to hold beyond the first day if the TICK is negative? Might I add to the trade if I see strength in the TICK?
We spend a lot of time studying entries, less time studying exits, but very little time truly studying the criteria that should keep us in or out of a trade. We might know the odds of success at the time we enter a trade, but can we update those odds based on current market movement to tell us whether to scale in or out? Sequence analysis would provide a rational basis for such updating, turning the management of trades into a lean process.
Saturday, February 25, 2006
More On Speculative Stocks - A Promising Predictor
What I'm finding in the very large baskets of Speculative and Non-Speculative issues that I am tracking is that they are more predictive of large index performance (such as ES, SPY, QQQQ, NQ) over longer timeframes than shorter ones. This has interesting implications for managing a trading portfolio to maximize opportunity. Increasingly I'm seeing where the common strategy of holding positions intraday only to minimize risk also minimizes important opportunities.
Let's take the current situation as an example. My basket of Speculative stocks is slightly down on the week. The Non-Speculative stocks, however, are up by over half a percent. Going back to March, 2003 (N = 743), I found 66 occasions in which the Spec stocks are down on the week by less than .40%. Ten days later, the S&P 500 Index (SPY) has been up by an average of .31% (41 up, 25 down), no different from the overall sample.
If we divide the sample in half based on the relative performance of Non-Spec stocks, a pattern emerges. When the Spec stocks are mildly weak on a five-day basis, but the Non-Spec stocks are strong (as at present), the next ten days in SPY are up by only .09% (17 up, 16 down). When the Spec stocks are mildly weak, but the Non-Spec stocks are weak, the next ten days in SPY are up by a whopping 1.22% (24 up, 9 down).
With the Non-Spec stocks leading the way at present, we'd have to count this as one for the bears going forward. We can see, however, that at holding periods of up to two weeks, the relative performance of Speculative issues and Non-Speculative issues seems to make quite a difference.
Let's take the current situation as an example. My basket of Speculative stocks is slightly down on the week. The Non-Speculative stocks, however, are up by over half a percent. Going back to March, 2003 (N = 743), I found 66 occasions in which the Spec stocks are down on the week by less than .40%. Ten days later, the S&P 500 Index (SPY) has been up by an average of .31% (41 up, 25 down), no different from the overall sample.
If we divide the sample in half based on the relative performance of Non-Spec stocks, a pattern emerges. When the Spec stocks are mildly weak on a five-day basis, but the Non-Spec stocks are strong (as at present), the next ten days in SPY are up by only .09% (17 up, 16 down). When the Spec stocks are mildly weak, but the Non-Spec stocks are weak, the next ten days in SPY are up by a whopping 1.22% (24 up, 9 down).
With the Non-Spec stocks leading the way at present, we'd have to count this as one for the bears going forward. We can see, however, that at holding periods of up to two weeks, the relative performance of Speculative issues and Non-Speculative issues seems to make quite a difference.
Friday, February 24, 2006
Semiconductors and QQQQ: An Example of Complexity
I've received quite a few emails regarding the last few entries dealing with lead-lag relationships between sectors/markets and the major trading indexes. Rarely are these relationships simple one-way affairs. Whether a sector leads or lags the trading index depends upon at least two crucial factors:
- Time Frame - A sector may be unrelated to an index on a very short-term basis, but still be predictive further out. For instance, many of the analyses are more powerful when predicting several days out than predicting next day.
- Whether the Predictor Sectors/Markets Are At Extremes or Moderate Values - Most often, a sector will not be equally predictive at very high and very low levels (extreme values) and at moderate levels. Analyses need to focus on a relevant segment of a predictor's distribution (a range of values similar to the current values), not the full distribution.
Here's a good example. We recently saw a leading relationship between the semiconductor stocks and the S&P 500. As of Friday's close, the semiconductor stocks (SMH) was down sharply on a two-day basis (down over 1.5%), while the NASDAQ 100 Index (QQQQ) was unchanged. In this situation, the SMH weakness ends up not leading the QQQQ lower. After a sharp two-day drop, most the indexes tend to rebound, which in this case would benefit the QQQQ.
We see that, since March, 2003 (N = 749), there were 90 days in which the two-day QQQQ neither rose nor fell by more than .20%. The next four days in QQQQ averaged a gain of .32% (51 up, 39 down), not significantly better than the average two-day gain of .30% for the sample overall.
When we split the sample in half based on SMH performance over the two days, we see a pattern. When SMH has been strong, the next four days in QQQQ average a gain of .11 (24 up, 21 down). When SMH has been weak (as recently), the next four days in QQQQ average a gain of .53% (27 up, 18 down). An examination of the data suggests that this occurs primarily because of a bounce back in SMH, which helps QQQQ.
What we're seeing is evidence of complexity. Trading relationships among sectors, stocks, and markets is not so simple as saying, "A leads B." One must specify the conditions under which there is a leading relationship. I have been encountering this same complexity with the earlier mentioned Speculative stocks and will report on that this weekend.
Thursday, February 23, 2006
Brokerage Stocks and the S&P: Another Leading Relationship
Here's another look at a market sector that has been exerting a lead relationship vis a vis the S&P 500 (SPY). It's the Broker-Dealer Index (XBD), which tracks the stocks of brokerage houses. One would think that if the XBD is healthy, that's a vote of confidence for the markets, and that should translate into favorable price action for SPY.
Over the past four days, we are essentially unchanged in SPY, but XBD is up by over 1%. I went back to March, 2003 (N = 744) and found 84 occasions in which SPY was neither up nor down more than .20% on a four-day basis. Over the next eight days, the average gain in SPY was .48% (52 up, 32 down). This compares with an average four-day gain in SPY of .50% (448 up, 296 down) for the sample overall. Clearly no great edge there.
When I divided the sample of little-changed SPY days in half, however, based on XBD performance, a pattern emerged. When XBD was strong, the next eight days in SPY averaged a very solid gain of .96% (31 up, 11 down). When XBD was weak, the next eight days in SPY averaged unchanged (21 up, 21 down). This suggests that bullish performance in XBD tends to anticipate bullish performance in SPY after we've had a narrow four days in the large caps. We'd have to count this as one for the bulls going forward.
Over the past four days, we are essentially unchanged in SPY, but XBD is up by over 1%. I went back to March, 2003 (N = 744) and found 84 occasions in which SPY was neither up nor down more than .20% on a four-day basis. Over the next eight days, the average gain in SPY was .48% (52 up, 32 down). This compares with an average four-day gain in SPY of .50% (448 up, 296 down) for the sample overall. Clearly no great edge there.
When I divided the sample of little-changed SPY days in half, however, based on XBD performance, a pattern emerged. When XBD was strong, the next eight days in SPY averaged a very solid gain of .96% (31 up, 11 down). When XBD was weak, the next eight days in SPY averaged unchanged (21 up, 21 down). This suggests that bullish performance in XBD tends to anticipate bullish performance in SPY after we've had a narrow four days in the large caps. We'd have to count this as one for the bulls going forward.
Wednesday, February 22, 2006
A Note on Trading Psychology
I just finished an email to someone at a trading firm in which I tried to summarize the essence of trading psychology in a single post. Here's the gist of what I had to say:
Under conditions of perceived risk and uncertainty (after all, what we react to is what we perceive) we no longer process information in our accustomed ways. At a brain level, regional cerebral blood flow shifts from the frontal cortex (our executive center) to motor centers that facilitate those famous flight or fight responses. This denies us access to our usual good planning, judgment, and decision making. As a result, we can end up making decisions that we look back upon in amazement: "What was I thinking?!" The answer, of course, is that we *weren't* thinking at the time. We were reacting: managing our perceptions of threat rather than the objective trades in front of us. Effective brief therapy for traders enables them to reprocess perceptions of risk and uncertainty, so that the blood shifts--and the associated state shifts that generate anxiety, frustration, and impulsive behavior--cannot occur.
My book The Psychology of Trading was an effort to explain this process and provide basic tools and techniques for traders to use under conditions of heightened risk and uncertainty. In the new book I'm currently writing, I will provide actual "therapy manuals" to help traders become their own therapists.
Anticipating market movements from historical studies provides a valuable edge in trading, but any edge is worthless if our states of mind prevent us from acting upon the information effectively. My hope is that the articles on my personal site, as well as the book, provide traders with some help on that front.
Under conditions of perceived risk and uncertainty (after all, what we react to is what we perceive) we no longer process information in our accustomed ways. At a brain level, regional cerebral blood flow shifts from the frontal cortex (our executive center) to motor centers that facilitate those famous flight or fight responses. This denies us access to our usual good planning, judgment, and decision making. As a result, we can end up making decisions that we look back upon in amazement: "What was I thinking?!" The answer, of course, is that we *weren't* thinking at the time. We were reacting: managing our perceptions of threat rather than the objective trades in front of us. Effective brief therapy for traders enables them to reprocess perceptions of risk and uncertainty, so that the blood shifts--and the associated state shifts that generate anxiety, frustration, and impulsive behavior--cannot occur.
My book The Psychology of Trading was an effort to explain this process and provide basic tools and techniques for traders to use under conditions of heightened risk and uncertainty. In the new book I'm currently writing, I will provide actual "therapy manuals" to help traders become their own therapists.
Anticipating market movements from historical studies provides a valuable edge in trading, but any edge is worthless if our states of mind prevent us from acting upon the information effectively. My hope is that the articles on my personal site, as well as the book, provide traders with some help on that front.
SOX and Stocks - Real Time
It's about 9 AM Chicago time as I'm writing this. The QQQQ opened higher this AM, but SMH was down on the open and some size was hitting bids in the semis. I know that there is a lead-lag relationship currently operative between "SOX and Stocks" so that alerted me to fade the opening strength rather than go with it. That trade idea paid out almost immediately in the first half hour.
Here's a further analysis: I looked back to March, 2003 and found 93 occasions in which the difference between SMH opened .5% or more weaker than QQQQ. From that open to the next day's close, the average price change in QQQQ was -.17% (38 up, 55 down), weaker than the average gain of .08% (380 up, 368 down) for the sample overall. Once again, we see SMH leading a relationship with a major stock average.
Applying these relationships to the proper time frames of trading is a big part of using them successfully. And, of course, one must keep in mind multiple lead-lag relationships, not just one involving a single trading instrument. When we see multiple leading relationships pointing the same way, that's when you can have real confidence in a trade idea.
Here's a further analysis: I looked back to March, 2003 and found 93 occasions in which the difference between SMH opened .5% or more weaker than QQQQ. From that open to the next day's close, the average price change in QQQQ was -.17% (38 up, 55 down), weaker than the average gain of .08% (380 up, 368 down) for the sample overall. Once again, we see SMH leading a relationship with a major stock average.
Applying these relationships to the proper time frames of trading is a big part of using them successfully. And, of course, one must keep in mind multiple lead-lag relationships, not just one involving a single trading instrument. When we see multiple leading relationships pointing the same way, that's when you can have real confidence in a trade idea.
Tuesday, February 21, 2006
SOX and Stocks: An Update
Much of my recent research posted here and on the Trading Markets site has dealt with lead-lag relationships in the market: identifying sectors that lead the major market indexes. One of my earliest investigations in this area was in an article I called "The SOX and the Stocks", in which I found that semiconductor stocks led the S&P 500 index.
I noticed today that, on a five-day basis, the S&P (SPY) is up by more than 1.6% but the semiconductor issues (SMH) is down by 1.35% over that same period. I decided to update my study by seeing what happens when these averages travel in different directions.
Since March, 2003 (N = 740), we have had 243 days in which SPY has been up more than 1% on a five-day basis. Five days later, SPY has averaged a gain of .17% (139 up, 104 down), considerably worse than the average gain of .30% (431 up, 309 down) for the sample overall.
When SPY has been up by more than 1% and SMH has been down more than 1% (N = 18), the next five days in SPY have averaged a loss of -.20% (9 up, 9 down). When SMH has been up more than 1% while SPY has also been up, the next have days in SPY have averaged a gain of .25% (109 up, 74 down).
It thus appears that strength in SPY is less likely to continue if it is not matched by strength in SMH--a factor we have to count as mildly bearish going forward.
Interestingly, I have found this relationship to hold on an intraday basis as well: It was the failure of SMH to break its previous day's highs early today that first alerted me to the possibility of a selloff.
I noticed today that, on a five-day basis, the S&P (SPY) is up by more than 1.6% but the semiconductor issues (SMH) is down by 1.35% over that same period. I decided to update my study by seeing what happens when these averages travel in different directions.
Since March, 2003 (N = 740), we have had 243 days in which SPY has been up more than 1% on a five-day basis. Five days later, SPY has averaged a gain of .17% (139 up, 104 down), considerably worse than the average gain of .30% (431 up, 309 down) for the sample overall.
When SPY has been up by more than 1% and SMH has been down more than 1% (N = 18), the next five days in SPY have averaged a loss of -.20% (9 up, 9 down). When SMH has been up more than 1% while SPY has also been up, the next have days in SPY have averaged a gain of .25% (109 up, 74 down).
It thus appears that strength in SPY is less likely to continue if it is not matched by strength in SMH--a factor we have to count as mildly bearish going forward.
Interestingly, I have found this relationship to hold on an intraday basis as well: It was the failure of SMH to break its previous day's highs early today that first alerted me to the possibility of a selloff.
Monday, February 20, 2006
Spec Stocks and the S&P: A Weekly View
This past week we saw the S&P 500 rise about 1.7% in a five day period. The performance of the Spec stocks was very similar. I decided to extend the recent investigations to a weekly basis by seeing what happens one week after a week in which SPY is up more than 1.5%.
Since March, 2003 (N = 744), we've had 156 days in which SPY has been up more than 1.5%. Five days later, the average gain for SPY has been .23% (91 up, 65 down), which is not greater than the five day average gain of .30% (435 up, 309 down) for the sample overall.
When we break the strong SPY days in half based on the relative performance of the Spec stocks, we see a similar pattern to one we've noticed with the daily data. When SPY is up more than 1.5% and Spec stocks are strong, the next five days in SPY average a gain of .35% (48 up, 31 down). When SPY is up strongly and Spec stocks are weak, the next five days in SPY average a gain of only .12% (43 up, 36 down).
I continue to refine my universe of Speculative and Non-Speculative issues and need to conduct more analyses with the Non-Spec group. Given that Spec stocks did not outperform SPY this past week, there is no bullish edge from this direction for the coming week.
On a separate note, check out my upcoming article for Trading Markets, which investigates SPY performance as a function of the Japanese market. I've also posted additional trading resources to the Trader Development page on my personal site.
Since March, 2003 (N = 744), we've had 156 days in which SPY has been up more than 1.5%. Five days later, the average gain for SPY has been .23% (91 up, 65 down), which is not greater than the five day average gain of .30% (435 up, 309 down) for the sample overall.
When we break the strong SPY days in half based on the relative performance of the Spec stocks, we see a similar pattern to one we've noticed with the daily data. When SPY is up more than 1.5% and Spec stocks are strong, the next five days in SPY average a gain of .35% (48 up, 31 down). When SPY is up strongly and Spec stocks are weak, the next five days in SPY average a gain of only .12% (43 up, 36 down).
I continue to refine my universe of Speculative and Non-Speculative issues and need to conduct more analyses with the Non-Spec group. Given that Spec stocks did not outperform SPY this past week, there is no bullish edge from this direction for the coming week.
On a separate note, check out my upcoming article for Trading Markets, which investigates SPY performance as a function of the Japanese market. I've also posted additional trading resources to the Trader Development page on my personal site.
Sunday, February 19, 2006
Speculative Stocks and the S&P 500
Continuing the investigations of the past couple of days, I redefined my Speculative and Non-Speculative stock universe to focus on larger companies more similar to those within the S&P 500. I also decided to compare Spec stock performance to the S&P 500 performance itself, rather than to Non-Spec performance.
In this study, I went back to March, 2003 (N = 746) and found 75 days in which SPY was up by 1% or more. Two days later, SPY was up by an average of .12% (44 up, 31 down). This is not significantly different from the average two-day gain in SPY for the sample overall: .12% (407 up, 339 down).
When I divided the strong SPY occasions in half, however, based on the relative performance of Spec stocks vs. SPY, a pattern again emerged--one compatible with my original hypothesis. When Spec stocks were strong, the next two days in SPY averaged a gain of .28% (24 up, 13 down). When Spec stocks were weak, the next two days in SPY averaged a loss of -.03% (20 up 18 down).
It thus appears that strength in the S&P 500 is more likely to continue in the short run when speculative stocks are outperforming the broad market. When speculative interest lags, strength in SPY is less likely to persist in the near term.
Using the same sample, I then looked at occasions when SPY was down by 1% or more (N = 72). Overall, when SPY has been weak in this manner, the next two days in SPY have averaged a gain of .30% (37 up, 35 down), stronger than the average two-day gain for the sample of .12% as outlined above.
When I divided the sample in half based on the relative performance of the Spec stocks vs. SPY, the pattern was more muted. When Spec stocks were relatively strong, the two days following a weak SPY averaged a gain of .36% (18 up, 18 down). When Spec stocks were relatively weak, the next two days averaged a gain of .23% (19 up, 17 down).
My next studies will look at the Non-Spec stocks; then I will extend the analyses to multi-day patterns.
In this study, I went back to March, 2003 (N = 746) and found 75 days in which SPY was up by 1% or more. Two days later, SPY was up by an average of .12% (44 up, 31 down). This is not significantly different from the average two-day gain in SPY for the sample overall: .12% (407 up, 339 down).
When I divided the strong SPY occasions in half, however, based on the relative performance of Spec stocks vs. SPY, a pattern again emerged--one compatible with my original hypothesis. When Spec stocks were strong, the next two days in SPY averaged a gain of .28% (24 up, 13 down). When Spec stocks were weak, the next two days in SPY averaged a loss of -.03% (20 up 18 down).
It thus appears that strength in the S&P 500 is more likely to continue in the short run when speculative stocks are outperforming the broad market. When speculative interest lags, strength in SPY is less likely to persist in the near term.
Using the same sample, I then looked at occasions when SPY was down by 1% or more (N = 72). Overall, when SPY has been weak in this manner, the next two days in SPY have averaged a gain of .30% (37 up, 35 down), stronger than the average two-day gain for the sample of .12% as outlined above.
When I divided the sample in half based on the relative performance of the Spec stocks vs. SPY, the pattern was more muted. When Spec stocks were relatively strong, the two days following a weak SPY averaged a gain of .36% (18 up, 18 down). When Spec stocks were relatively weak, the next two days averaged a gain of .23% (19 up, 17 down).
My next studies will look at the Non-Spec stocks; then I will extend the analyses to multi-day patterns.
Saturday, February 18, 2006
Speculative and Non-Speculative Stocks: Surprise Findings
To follow up on the Speculative and Non-Speculative stock research from my last posting, I decided to look at up days in the S&P 500 (SPY) and whether the relative performance of the Spec and Non-Spec stocks (many of which are not stocks in the S&P large cap universe) made a difference in future performance.
Since April, 2003 (N = 715), we had 69 days in which SPY was up by 1% or greater. Overall, the market was up by an average of .21% three days later (46 up, 23 down), a bit better than the average three-day gain of .16% (423 up, 292 down) for the sample overall.
I then broke the strong SPY days in half based upon the relative strength of the Spec stocks vs. the Non-Spec issues. (See yesterday's blog entry for a description of these stocks). To my surprise--and contrary to my initial hypothesis--when the Spec stocks were relatively strong, the next three days in SPY averaged a gain of only .05% (23 up, 12 down). When the Non-Spec stocks were relatively strong, the next three days in SPY averaged a gain of .36% (23 up, 11 down).
This suggests that strength in SPY is more likely to continue in the near term if Non-Speculative stocks (some of which are highly weighted in the S&P) are strong relative to Speculative issues.
When I examined weak S&P days--those down by 1% or more (N = 67) in the same sample--another interesting pattern emerged. Overall, when the market is down by over 1%, the next two days in SPY average a gain of .26% (34 up, 33 down). This is modestly better than the average two-day gain for the entire sample of .11% (392 up, 323 down).
When we divide the weak SPY days in half based on the relative strength of the Spec stocks, the results are eye-opening. When the Spec stocks are relatively strong during a weak day in SPY (N = 33), the next two days in SPY average a gain of .60% (20 up, 13 down). When the Spec stocks are relatively weak during a weak day in SPY (N = 34), the next two days in SPY average a loss of -.06% (14 up, 20 down).
This is quite a difference. It suggests that the S&P is more likely to rebound from weakness in the near term if Spec stocks are displaying relative strength. If Non-Spec stocks are relatively stronger, the weakness in SPY is more likely to continue in the short run.
In sum, a strong day in SPY is more likely to continue its rise if Non-Spec stocks are relatively strong. A weak day in SPY is more likely to reverse if Spec stocks are relatively strong. The latter effect appears stronger than the former.
I have much more exploration to do with this measure. The relationship between the relative performance of Spec and Non-Spec stocks and future market performance appears to be more complex than I initially envisioned. There are meaningful relationships here, and the key will be to identify and explain them. I will post more on this topic on my Trader Performance blog tonight.
Since April, 2003 (N = 715), we had 69 days in which SPY was up by 1% or greater. Overall, the market was up by an average of .21% three days later (46 up, 23 down), a bit better than the average three-day gain of .16% (423 up, 292 down) for the sample overall.
I then broke the strong SPY days in half based upon the relative strength of the Spec stocks vs. the Non-Spec issues. (See yesterday's blog entry for a description of these stocks). To my surprise--and contrary to my initial hypothesis--when the Spec stocks were relatively strong, the next three days in SPY averaged a gain of only .05% (23 up, 12 down). When the Non-Spec stocks were relatively strong, the next three days in SPY averaged a gain of .36% (23 up, 11 down).
This suggests that strength in SPY is more likely to continue in the near term if Non-Speculative stocks (some of which are highly weighted in the S&P) are strong relative to Speculative issues.
When I examined weak S&P days--those down by 1% or more (N = 67) in the same sample--another interesting pattern emerged. Overall, when the market is down by over 1%, the next two days in SPY average a gain of .26% (34 up, 33 down). This is modestly better than the average two-day gain for the entire sample of .11% (392 up, 323 down).
When we divide the weak SPY days in half based on the relative strength of the Spec stocks, the results are eye-opening. When the Spec stocks are relatively strong during a weak day in SPY (N = 33), the next two days in SPY average a gain of .60% (20 up, 13 down). When the Spec stocks are relatively weak during a weak day in SPY (N = 34), the next two days in SPY average a loss of -.06% (14 up, 20 down).
This is quite a difference. It suggests that the S&P is more likely to rebound from weakness in the near term if Spec stocks are displaying relative strength. If Non-Spec stocks are relatively stronger, the weakness in SPY is more likely to continue in the short run.
In sum, a strong day in SPY is more likely to continue its rise if Non-Spec stocks are relatively strong. A weak day in SPY is more likely to reverse if Spec stocks are relatively strong. The latter effect appears stronger than the former.
I have much more exploration to do with this measure. The relationship between the relative performance of Spec and Non-Spec stocks and future market performance appears to be more complex than I initially envisioned. There are meaningful relationships here, and the key will be to identify and explain them. I will post more on this topic on my Trader Performance blog tonight.
Friday, February 17, 2006
Potentially Explosive Research: Spec vs. Non Spec Stocks
The best market indicators, I've found, are the ones that are the least picked over. I can pretty much assure you that if an indicator can be readily created in a charting application, it is of limited predictive value. Been there, done that.
Good indicators, on the other hand, are conceptually grounded and are not easily replicated. The Demand/Supply Index on my Trading Psychology Weblog is an example. It is a straightforward measure of momentum, but is so broad--covering every operating company stock on the major exchanges-- and is so calculation intensive (requiring prices and volatility estimates at two different time frames for each issue) that it's unlikely to appear any time soon on the indicator menu of a trading app.
The indicator I'm working on now has considerable promise for these reasons. I divide a very large stock universe into two components: speculative and non-speculative. Spec stocks tend to be more volatile in their price behavior, younger as firms, more volatile in their earnings, more likely to trade at high price earnings ratios, less likely to pay dividends, and less likely to have a large percentage of their shares owned by institutions. Non-Spec stocks are less volatile, more established as companies, more stable in their earnings, more likely to trade at lower price earnings ratios, more likely to pay dividends, and more likely to have significant institutional coverage. As a whole, Spec stocks show better growth than Non-Spec stocks, but this may be a function of survivor bias. There are plenty of Spec stocks that show earnings declines, and plenty of Non-Spec stocks that show steady earnings gains.
In my first analysis, I created a synthetic market index consisting of half Spec stocks and half Non-Spec stocks. I then looked at occasions when price change in this index is narrow on the day (up or down less than .30%). Since April, 2003 (N = 715), we had 151 narrow days in the index. When the Spec issues were strong on those narrow days (N = 75), the next two days in the synthetic index were up by an average of .33% (47 up, 28 down). When the Non-Spec issues were strong on those narrow days (N = 76), the synthetic index over the next two days was up by an average of .03% (35 up, 41 down).
What this means is that both Spec and Non-Spec stocks (the synthetic index as a whole) perform better when relative strength is on the side of the Spec stocks. This makes sense: when sentiment is favorable in the market, traders will prefer Speculative issues. When sentiment is cautious, traders will lean toward safer, Non-Spec stocks.
There is much research to follow from this, including--of course--predicting the major market averages from the baskets of Spec and Non-Spec issues and creating a Spec Index indicator to track daily speculative sentiment in the market. I have a feeling this one is a winner.
Good indicators, on the other hand, are conceptually grounded and are not easily replicated. The Demand/Supply Index on my Trading Psychology Weblog is an example. It is a straightforward measure of momentum, but is so broad--covering every operating company stock on the major exchanges-- and is so calculation intensive (requiring prices and volatility estimates at two different time frames for each issue) that it's unlikely to appear any time soon on the indicator menu of a trading app.
The indicator I'm working on now has considerable promise for these reasons. I divide a very large stock universe into two components: speculative and non-speculative. Spec stocks tend to be more volatile in their price behavior, younger as firms, more volatile in their earnings, more likely to trade at high price earnings ratios, less likely to pay dividends, and less likely to have a large percentage of their shares owned by institutions. Non-Spec stocks are less volatile, more established as companies, more stable in their earnings, more likely to trade at lower price earnings ratios, more likely to pay dividends, and more likely to have significant institutional coverage. As a whole, Spec stocks show better growth than Non-Spec stocks, but this may be a function of survivor bias. There are plenty of Spec stocks that show earnings declines, and plenty of Non-Spec stocks that show steady earnings gains.
In my first analysis, I created a synthetic market index consisting of half Spec stocks and half Non-Spec stocks. I then looked at occasions when price change in this index is narrow on the day (up or down less than .30%). Since April, 2003 (N = 715), we had 151 narrow days in the index. When the Spec issues were strong on those narrow days (N = 75), the next two days in the synthetic index were up by an average of .33% (47 up, 28 down). When the Non-Spec issues were strong on those narrow days (N = 76), the synthetic index over the next two days was up by an average of .03% (35 up, 41 down).
What this means is that both Spec and Non-Spec stocks (the synthetic index as a whole) perform better when relative strength is on the side of the Spec stocks. This makes sense: when sentiment is favorable in the market, traders will prefer Speculative issues. When sentiment is cautious, traders will lean toward safer, Non-Spec stocks.
There is much research to follow from this, including--of course--predicting the major market averages from the baskets of Spec and Non-Spec issues and creating a Spec Index indicator to track daily speculative sentiment in the market. I have a feeling this one is a winner.
Thursday, February 16, 2006
Looking At Sector Leaders: Banks
Check out the Trading Markets site Friday AM; I should have a detailed article on this topic posted then. Over the past three sessions, we are up more than 2% in both SPY and the banking stock index BKX. I decided to look at what happens when this is the case.
Since March, 2003 (N = 743) we have had 50 days in which SPY has been up by more than 2%. Over the next five days, SPY has averaged a gain of .55% (33 up, 17 down), which is stronger than the average five-day gain of .30% (434 up, 309 down) for the sample overall.
Interestingly, however, when SPY and BKX are both up more than 2% in a three day period (N = 36), the next five days in SPY average a gain of .95% (24 up, 12 down). When SPY is up by more than 2% in a three-day period, but BKX is up less than 2% (N = 14), the next five days in SPY average a loss of -.48% (7 up, 7 down).
In short, the bullish prospects for SPY appear to be better when banking stocks are participating in market strength. We'll count this as a positive for the bulls going forward.
Since March, 2003 (N = 743) we have had 50 days in which SPY has been up by more than 2%. Over the next five days, SPY has averaged a gain of .55% (33 up, 17 down), which is stronger than the average five-day gain of .30% (434 up, 309 down) for the sample overall.
Interestingly, however, when SPY and BKX are both up more than 2% in a three day period (N = 36), the next five days in SPY average a gain of .95% (24 up, 12 down). When SPY is up by more than 2% in a three-day period, but BKX is up less than 2% (N = 14), the next five days in SPY average a loss of -.48% (7 up, 7 down).
In short, the bullish prospects for SPY appear to be better when banking stocks are participating in market strength. We'll count this as a positive for the bulls going forward.
Wednesday, February 15, 2006
Strong Stocks, Weak Oil: What Next?
In the past two days, the S&P 500 (SPY) has risen by over 1.4%, while the oil and gas stocks ($XOI) have dropped by over 1.26%. My thought was that this configuration would be bullish for SPY, as it suggests a favorable outlook for companies in the face of falling oil prices.
Since January, 2003 (N = 782), we have had 14 days in which the two-day SPY has been up by over 1% but the oil stocks have been down by .9% or more on a two-day basis. This is an unusual configuration, as daily price changes in SPY and XOI correlate by over .50. Five days later, SPY was up by an average 1.09% (10 up, 4 down). This is much stronger than the average five-day price change for the sample (.22%) and for periods in which SPY has been up by more than 1% over two days (.33%; N = 151).
This is admittedly a small sample, and in the very near term, it has not paid to buy stocks after a two-day runup. Still, the non-oil components of the weighted large cap indexes must be strong to overcome the weakness in the energy issues--strength that appears to carry over to the following several days of trading.
Since January, 2003 (N = 782), we have had 14 days in which the two-day SPY has been up by over 1% but the oil stocks have been down by .9% or more on a two-day basis. This is an unusual configuration, as daily price changes in SPY and XOI correlate by over .50. Five days later, SPY was up by an average 1.09% (10 up, 4 down). This is much stronger than the average five-day price change for the sample (.22%) and for periods in which SPY has been up by more than 1% over two days (.33%; N = 151).
This is admittedly a small sample, and in the very near term, it has not paid to buy stocks after a two-day runup. Still, the non-oil components of the weighted large cap indexes must be strong to overcome the weakness in the energy issues--strength that appears to carry over to the following several days of trading.
Tuesday, February 14, 2006
Strong Upward Momentum: What Follows
Readers of the Trading Psychology Weblog are familiar with the Demand/Supply measure, which is a proprietary indicator of momentum that I post daily to the site. Demand is the number of listed U.S. operating company stocks that closed above the volatility envelope surrounding both a short-term moving average and an intermediate-term average. These, therefore, are stocks with very strong price momentum. Supply is the number of issues that close below both averages. It is common for Demand and Supply to hit extremes prior to price peaks and valleys in the major averages.
Since the start of the bull market (N = 729), we have had 44 days in which the Demand reading has exceeded 120. (Tuesday's reading was over 130, reflecting the solid rally; please note that these are normalized values, not raw figures). Three days after such strong momentum, the market was up by an average of .52% (33 up, 11 down). This is much stronger than the average three day gain of .18% (432 up, 297 down) for the sample overall. Strong upside momentum tends to persist in the short run: this finding has been valid throughout the bull market.
Since the start of the bull market (N = 729), we have had 44 days in which the Demand reading has exceeded 120. (Tuesday's reading was over 130, reflecting the solid rally; please note that these are normalized values, not raw figures). Three days after such strong momentum, the market was up by an average of .52% (33 up, 11 down). This is much stronger than the average three day gain of .18% (432 up, 297 down) for the sample overall. Strong upside momentum tends to persist in the short run: this finding has been valid throughout the bull market.
Monday, February 13, 2006
Small and Midcap Stocks - Relative Performance
This is the first of my attempts to carefully separate out the small and mid cap universes by comparing the S&P 400 small caps ($SML) to the S&P 600 mid caps ($MID). I went back to March, 2004 (N = 482) and found 77 occasions in which SML was down by more than 1%--as was the case on Monday. I then investigated whether the relative performance of MID vs. SML had any impact on future short-term performance.
When SML has been down by 1% or more (N = 77), the next day in SML has averaged a gain of only .01% (41 up, 36 down). This offers no edge relative to the sample overall, which averages a gain of .06% (267 up, 215 down).
I then broke down the weak SML days in half based on MID performance. When SML was much weaker than MID (N = 38), the next day in SML averaged .20% (24 up, 14 down). When MID showed greater relative strength (N = 39), the next day in SML averaged a loss of -.18% (18 up, 21 down).
On Monday, SML was weak relative to MID, but not by a huge margin. Interestingly, it appears that, although SML and MID are highly correlated, relative weakness among the smallest stocks during a decline leads to a reversal, while relative strength leads to further weakness.
Because the Russell 2000 Index has components of both small and midcap issues, a differentiation of these might be helpful in predicting ER2 performance. That will be an upcoming project.
When SML has been down by 1% or more (N = 77), the next day in SML has averaged a gain of only .01% (41 up, 36 down). This offers no edge relative to the sample overall, which averages a gain of .06% (267 up, 215 down).
I then broke down the weak SML days in half based on MID performance. When SML was much weaker than MID (N = 38), the next day in SML averaged .20% (24 up, 14 down). When MID showed greater relative strength (N = 39), the next day in SML averaged a loss of -.18% (18 up, 21 down).
On Monday, SML was weak relative to MID, but not by a huge margin. Interestingly, it appears that, although SML and MID are highly correlated, relative weakness among the smallest stocks during a decline leads to a reversal, while relative strength leads to further weakness.
Because the Russell 2000 Index has components of both small and midcap issues, a differentiation of these might be helpful in predicting ER2 performance. That will be an upcoming project.
Sunday, February 12, 2006
Small Price Change, High Volatility
Friday's market closed only modestly higher after first dropping, then rising, and finally falling back toward its opening price. That had me looking at markets that are little changed but have above average daily trading ranges.
Since March, 2003 (N = 734), we have had 198 days in which SPY has closed within .20% of its opening price. Three days later, the market is up by an average .29% (120 up, 78 down). This is stronger than the average change of .15% (313 up, 223 down) for the remainder of the sample.
When we look at narrow SPY days as a function of volatility (daily range), however, a pattern emerges. When the range is wider (N = 99), the following three days average a gain of .40% (62 up, 37 down). When the range is narrower (N = 99), the following three days average a gain of .17% (58 up, 41 down). This suggests that wide range days with small price change have more favorable expectations than narrow days with small price change.
Interestingly, this pattern has continued throughout the recent bull market. Of the 12 occasions since August, 2004 in which we have had a range above 1% and narrow price change from open to close, 10 have shown gains over the next three days, averaging .71%. We'd have to score this one for the bulls as we start the new week.
Since March, 2003 (N = 734), we have had 198 days in which SPY has closed within .20% of its opening price. Three days later, the market is up by an average .29% (120 up, 78 down). This is stronger than the average change of .15% (313 up, 223 down) for the remainder of the sample.
When we look at narrow SPY days as a function of volatility (daily range), however, a pattern emerges. When the range is wider (N = 99), the following three days average a gain of .40% (62 up, 37 down). When the range is narrower (N = 99), the following three days average a gain of .17% (58 up, 41 down). This suggests that wide range days with small price change have more favorable expectations than narrow days with small price change.
Interestingly, this pattern has continued throughout the recent bull market. Of the 12 occasions since August, 2004 in which we have had a range above 1% and narrow price change from open to close, 10 have shown gains over the next three days, averaging .71%. We'd have to score this one for the bulls as we start the new week.
Saturday, February 11, 2006
A Longer-Term Look at the Market
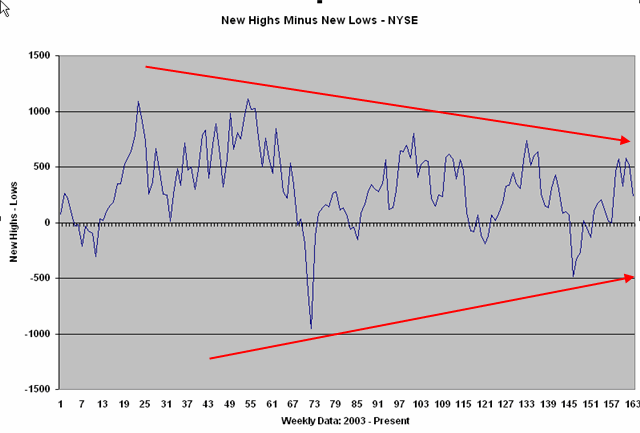 Here you can see weekly new highs minus weekly new lows for the NYSE, 2003 - present. The pattern is quite clear: we're seeing fewer stocks participate during market rallies, but we're also seeing modest levels of new lows. In all, this is consistent with low volatility market conditions, and it is also consistent with past bull market patterns.
In general, we see several phases to a market cycle. The earliest phase of the bull is one of great momentum, with a majority of issues participating and making new highs. As the bull matures, we continue to see price highs for most indices, but a declining number of individual issues making new highs. Late in the bull market, new lows will expand, new highs will dwindle, and the indices will fail to make new price highs on rallies. This sets up a phase of bear market selling, with new lows consistently exceeding new highs--interrupted by brief short-covering rallies--followed by a washout period of capitulation in which new lows vastly outnumber new highs.
Using this broad schematic, we can see that we're still in the phase of the bull where we have made new price highs but with decreased participation from individual stocks. It is normal to experience a pullback following such rallies; these bear swings are generally prefaced by an expansion in the number of stocks making new lows. As long as we do not see a more negative new high/low balance than was recorded at the October lows, I will not worry overmuch about the bull market. A signficant expansion of new lows would, IMHO, be of greater concern.
The aging of the bull is generally also heralded by shifts in market leadership. We saw this during the market peak around 2000-2001. Speculative favorites give way to more defensive stocks as economic concerns come to the fore. The current collapse of such favorites as GOOG and YHOO, as well as the gold and oil stocks, is on my radar for that reason.
In short, it looks to me as though we're in a mature bull market, but not one that is yet showing signs of imminent collapse. This doesn't affect my day-to-day trading outlook greatly, but is relevant to longer-term trading and investing horizons. I am very open to the possibility that the early January highs were the price highs for this bull market, but will not stay fixed in that view if the ES can sustain a low in the mid 1250s.
Friday, February 10, 2006
Thinking About Historical Analyses
I'll take a break today from the historical analyses to highlight several issues when using historical data to define possible trading edges:
1) All such analyses provide hypotheses only, not conclusions. The historical analyses are not "right" if they are replayed in the upcoming markets; nor are they "wrong" if the historical odds are not manifested on the next occasion. The historical studies merely indicate what has occurred in the past and whether such occurrences have been skewed or not. Our job is to use this information as background and see if the obtained patterns are indeed playing themselves out in the market. As I mentioned in a recent article for The Traders Journal in Singapore, Pasteur's observation that "Chance favors the prepared mind" captures the intent of historical study. It is meant as preparation--not as a fixed opinion to get locked into.
2) Disconfirmed hypotheses also provide information. Excellent trade ideas can be derived once you identify that a market is behaving contrary to its historical norms.
3) The utility and validity of historical analyses depends not only on having clean data and a promising set of indicators to study, but also on selecting proper lookback periods. The patterns that were common during the 2000-2002 bear market are not patterns we've seen in the past 2-3 years. Nor will the patterns of 2008 replicate those of the recent past. Recently, we've seen that patterns that were strong early in the current bull market (2003-4) are no longer robust. This means that we must weight recent data more strongly and be open to the possibility that we are undergoing a market transition. Indeed, shifts of trending and volatility patterns are perhaps the best evidence we have that market cycles are shifting.
4) The utility and validity of historical analyses also depends upon lookforward periods. Forecasting directional tendencies 1-3 days in the future requires a different set of predictors than forecasting 1-3 months or years hence. Of particular importance is what I call the optimum predictive horizon: the time frame that is most reliably forecast with a given set of predictors. This horizon, which almost always is not intraday, can help one define a directional bias within which shorter-term trading can occur.
5) Historical analyses are best employed in combination, with different sets of predictors and timeframes. Occasions in which multiple analyses converge to yield similar directional biases provide very high confidence trade ideas. Occasions when multiple analyses generate no meaningful directional biases help alert us to markets where our edge might be slim to none. Much of total P/L comes from trading known edges aggressively and staying away from risk when there is no edge--something any good poker player knows.
I will follow up with further thoughts on the Trader Performance blog of my personal site. Thanks for the many kind comments and suggestions I've received regarding the TraderFeed blog.
Brett
1) All such analyses provide hypotheses only, not conclusions. The historical analyses are not "right" if they are replayed in the upcoming markets; nor are they "wrong" if the historical odds are not manifested on the next occasion. The historical studies merely indicate what has occurred in the past and whether such occurrences have been skewed or not. Our job is to use this information as background and see if the obtained patterns are indeed playing themselves out in the market. As I mentioned in a recent article for The Traders Journal in Singapore, Pasteur's observation that "Chance favors the prepared mind" captures the intent of historical study. It is meant as preparation--not as a fixed opinion to get locked into.
2) Disconfirmed hypotheses also provide information. Excellent trade ideas can be derived once you identify that a market is behaving contrary to its historical norms.
3) The utility and validity of historical analyses depends not only on having clean data and a promising set of indicators to study, but also on selecting proper lookback periods. The patterns that were common during the 2000-2002 bear market are not patterns we've seen in the past 2-3 years. Nor will the patterns of 2008 replicate those of the recent past. Recently, we've seen that patterns that were strong early in the current bull market (2003-4) are no longer robust. This means that we must weight recent data more strongly and be open to the possibility that we are undergoing a market transition. Indeed, shifts of trending and volatility patterns are perhaps the best evidence we have that market cycles are shifting.
4) The utility and validity of historical analyses also depends upon lookforward periods. Forecasting directional tendencies 1-3 days in the future requires a different set of predictors than forecasting 1-3 months or years hence. Of particular importance is what I call the optimum predictive horizon: the time frame that is most reliably forecast with a given set of predictors. This horizon, which almost always is not intraday, can help one define a directional bias within which shorter-term trading can occur.
5) Historical analyses are best employed in combination, with different sets of predictors and timeframes. Occasions in which multiple analyses converge to yield similar directional biases provide very high confidence trade ideas. Occasions when multiple analyses generate no meaningful directional biases help alert us to markets where our edge might be slim to none. Much of total P/L comes from trading known edges aggressively and staying away from risk when there is no edge--something any good poker player knows.
I will follow up with further thoughts on the Trader Performance blog of my personal site. Thanks for the many kind comments and suggestions I've received regarding the TraderFeed blog.
Brett
Thursday, February 09, 2006
QQQQ: Reversal Days and Changing Cycles
Thursday's NASDAQ Index (QQQQ) turned in a reversal day, opening near the day's highs and closing near the lows. It was also a relatively wide range day compared to recent action, with a range slightly over 1.8%. We closed about 1.6% off the day's highs and .20% off the lows.
I examined days since March, 2003 (N = 733) to identify past occasions when we've closed off the highs by more than 1.5% and off the lows by less than .30% (N = 66). Three days after these reversal days, the market was up by an average of .50% (38 up, 28 down), stronger than the .22% (416 up, 317 down) for the sample overall.
When I broke the sample in half based on time, however, a pattern emerged. From May, 2004 to the present (N = 33), the average three-day change following a reversal day was .08% (18 up, 15 down). From March, 2003 through April, 2004, the average three-day change was .91% (20 up, 13 down).
Interestingly, returns following the reversal day were superior when the prior day was weak rather than strong. Both of these patterns fail to provide us with favorable near term bullish edges and, indeed, suggest subnormal returns in the short run.
I examined days since March, 2003 (N = 733) to identify past occasions when we've closed off the highs by more than 1.5% and off the lows by less than .30% (N = 66). Three days after these reversal days, the market was up by an average of .50% (38 up, 28 down), stronger than the .22% (416 up, 317 down) for the sample overall.
When I broke the sample in half based on time, however, a pattern emerged. From May, 2004 to the present (N = 33), the average three-day change following a reversal day was .08% (18 up, 15 down). From March, 2003 through April, 2004, the average three-day change was .91% (20 up, 13 down).
Interestingly, returns following the reversal day were superior when the prior day was weak rather than strong. Both of these patterns fail to provide us with favorable near term bullish edges and, indeed, suggest subnormal returns in the short run.
Wednesday, February 08, 2006
Put/Call Ratio: Does It Make A Difference?
I noticed that we continue to have a relatively high equity put/call ratio despite Wednesday's rise. The five-day put-call ratio is the highest we've seen in 2006. To see if the ratio makes a difference, I looked at all days since March, 2003 (N = 737) in which SPY was up over .5% and the one-day put/call ratio was over .75.
Overall, we've had 191 days in which SPY was up over .5%. When the put/call ratio was over .75 (N = 37), the market three days later was up by an average .51% (24 up, 13 down). When the put/call ratio was below .75, however, the market three days later was up by a subnormal .03% (86 up, 68 down). It appears that rises have a better chance of continuing to the upside in the short run when sentiment remains bearish, as is the case at present.
I will continue to investigate the equity put/call ratio and report results here and on my personal site. Note that this is the ratio for stocks only, eliminating the hedging bias from options transactions on indices.
Overall, we've had 191 days in which SPY was up over .5%. When the put/call ratio was over .75 (N = 37), the market three days later was up by an average .51% (24 up, 13 down). When the put/call ratio was below .75, however, the market three days later was up by a subnormal .03% (86 up, 68 down). It appears that rises have a better chance of continuing to the upside in the short run when sentiment remains bearish, as is the case at present.
I will continue to investigate the equity put/call ratio and report results here and on my personal site. Note that this is the ratio for stocks only, eliminating the hedging bias from options transactions on indices.
Tuesday, February 07, 2006
Weak Russell 2000 Index and the NYSE TICK
Tuesday saw a downside breakout and a loss of over 1.5% in the Russell 2000 stock average (IWM). I decided to look at what happens after large Russell declines of over 1.5% as a function of broad selling in the market. This selling, readers of my Trading Psychology Weblog know, is measured by the Adjusted TICK: the NYSE TICK adjusted for a zero mean.
Since July, 2003 (N = 653), we've had 64 days in which IWM has been down 1.5% or more. The next day, IWM has averaged a loss of -.03% (32 up, 32 down), which is weaker than the average daily gain of .08% (353 up, 300 down) for the sample overall.
When we divide the sample in half based on the Adjusted TICK, however, a pattern emerges. When the TICK is weak (N = 32), the next day in IWM averages a loss of -.22% (14 up, 18 down). When the TICK is strong (N = 32), the next day in IWM averages a gain of .16% (18 up, 14 down). Tuesday saw a TICK reading in the strong end of the sample, suggesting lesser odds of carryover selling on Wednesday.
Interestingly, when we look three days out after a weak day in IWM, expectations have been favorable. The market has averaged a three-day gain of .51% (39 up, 25 down), better than the average gain of .22% (384 up, 269 down) for the sample overall. In general, buying weakness after a weak day in IWM has been a solid strategy during the bull market.
Since July, 2003 (N = 653), we've had 64 days in which IWM has been down 1.5% or more. The next day, IWM has averaged a loss of -.03% (32 up, 32 down), which is weaker than the average daily gain of .08% (353 up, 300 down) for the sample overall.
When we divide the sample in half based on the Adjusted TICK, however, a pattern emerges. When the TICK is weak (N = 32), the next day in IWM averages a loss of -.22% (14 up, 18 down). When the TICK is strong (N = 32), the next day in IWM averages a gain of .16% (18 up, 14 down). Tuesday saw a TICK reading in the strong end of the sample, suggesting lesser odds of carryover selling on Wednesday.
Interestingly, when we look three days out after a weak day in IWM, expectations have been favorable. The market has averaged a three-day gain of .51% (39 up, 25 down), better than the average gain of .22% (384 up, 269 down) for the sample overall. In general, buying weakness after a weak day in IWM has been a solid strategy during the bull market.
Monday, February 06, 2006
Narrow, Slow Days In the QQQQ
Monday was a slow day in the market, with the NASDAQ 100 (QQQQ) Index moving in a roughly 1% range--about 2/3 the norm. The QQQQ also traded at about 70% of its average volume over the past 60 days, closing down .22% from open to close. I decided to take a look at slow, narrow days in QQQQ by going back to March, 2003 (N = 737) and investigating days in which the range was less than 1.2% and volume was 80% of the 60 day average or less. This provided a sample of 105 occasions.
As we might expect, the next day in QQQQ also tends to be slow. Fully 76 of the 105 occasions were below average in volume. This tended to produce reduced trading ranges; 74 of the occasions were below average in trading range.
Interestingly, when the narrow, slow day was down (N = 42), the market fared better the next day (average gain = .14%; 26 up, 16 down) than if the narrow slow day was up (N = 63; average loss = -.03%; 27 up, 36 down).
In short, narrow slowness tends to carry over to the next day for QQQQ, but price movement on the narrow slow day tends to reverse the following day.
As we might expect, the next day in QQQQ also tends to be slow. Fully 76 of the 105 occasions were below average in volume. This tended to produce reduced trading ranges; 74 of the occasions were below average in trading range.
Interestingly, when the narrow, slow day was down (N = 42), the market fared better the next day (average gain = .14%; 26 up, 16 down) than if the narrow slow day was up (N = 63; average loss = -.03%; 27 up, 36 down).
In short, narrow slowness tends to carry over to the next day for QQQQ, but price movement on the narrow slow day tends to reverse the following day.
Sunday, February 05, 2006
Weakness and Day-of-Week
I just submitted an article that should appear Monday AM on the Trading Markets site. This one looked at two-day declines of more than one percent and the returns expectable as a function of day-of-the-week. The bottom line was that, since 2003, Mondays, Tuesdays, and Fridays returned much better results than Wednesday and Thursday. Indeed, the latter two days barely were profitable. What was most interesting was that I obtained these exact same results from S&P 500 data going back to 1995. It is very difficult to believe that this is pure chance--occurring as it does over independent data samples going back over a decade--yet it is difficult to explain why certain days should perform differently from others. Would we see similar findings for market rises? For other time frames? Clearly this is an area that warrants further investigation. For what it's worth, weakness early in the week is particularly associated with reversals; weakness at the end of Wednesday or Thursday is not. Buying weakness at the end of Monday has worked particularly well since 2003. I will be following up on my personal site.
Saturday, February 04, 2006
Days of the Week: Do They Make a Difference?

Traders often refer to Fridays as bad trading days...Mondays fare almost as poorly in their reputation. But are there real differences in trading patterns from day to day?
I went back to January, 2003 and investigated results for each day of the week. My first finding was that volatility was about the same for the various days. There was no evidence that any particular day of the week had more movement than any other.
Since the beginning of 2003, we have gained almost 400 S&P points. Close to 70% of this total occurred on Monday and Tuesday. Wednesday showed very slightly negative returns, Thursday had the third best performance, and Friday was barely positive. Over 90% of all market gains since 2003 have occurred on Monday, Tuesday, and Thursday.
Here are the specific average daily changes:
Monday: .096% (83 up, 61 down, 155.21 points)
Tuesday: .081% (91 up, 69 down, 118.21 points)
Wednesday: -.003% (86 up, 74 down, -1.87 points)
Thursday: .065% (87 up, 69 down, 95.83 points)
Friday: .024% (83 up, 74 down, 28.93 points)
As you might guess, the best returns came from buying at the end of Wednesday and holding through Monday (.18%) or buying the end of Thursday and holding through Tuesday (.19%). Buying a down Friday and holding through Monday (a strategy that applies to the current market) has been quite a winning trade idea: average one-day price change is .21 (47 up, 24 down).
Friday, February 03, 2006
Two-Day Declines: Important, Shifting Expectations

Friday's market gave us an opportunity for an interesting analysis. We've been down two consecutive days, for a total decline of -1.65% on SPY. When we've been down two days in a row for a drop in excess of 1.5%, what happens next?
Since January, 2003 (N = 774), we've had 49 such two-day sequences. The next day, the market is up on average .14% (32 up, 17 down). This is stronger than the average one-day gain of .05% (430 up 344 down) for the sample overall. It thus looks as though a bounce is the normal expectation following two consecutive declines.
When we divide the sample by time, however, a different picture emerges. During 2003 (N = 25), the two-day declines led to a next-day average price change of .38% (18 up, 7 down)--quite strong. In 2004 and 2005, however (N = 24), the average next day change has been -.11% (14 up, 10 down).
If we look three days out, the pattern becomes even more pronounced. During 2003, the average change over the next three days following the two-day drop was .25% (15 up, 10 down). Since 2004, the average three-day change after a two-day drop was .08% (13 up, 11 down)--and in 2005 alone (N = 10), the average three-day change has been -.17% (3 up, 7 down)!
What this is telling us is that early in the bull market, expectations following a two-day drop were quite positive, but these positive expectations have been eroding. At present, based on 2004 and 2005 results, we cannot say that there is a distinctive upside edge following a large two-day decline, and there is even modest evidence of continuation to the downside.
Such sequential analyses of patterns are useful in identifying changing market cycles. This is very important.
Very.
Thursday, February 02, 2006
Quick Finding With the NYSE TICK
An upcoming article on the Trading Markets site will detail expectations when one-day declines are accompanied by very negative Adjusted TICK values. The Adjusted TICK is a staple of analysis on my personal site; it is the NYSE TICK adjusted to create a zero mean. The gist of the article is that days such as Thursday, which had a very weak Adjusted TICK and a decline in excess of 1%, have weaker expectations the following day than 1% declining days with stronger TICK readings. This, along with the relatively broad momentum weakness in the market, has me more cautious about the market upside than I would normally be after hitting a five-day low. (See previous entry).
Large Decline & A Five Day Low
Thursday's decline came very close to one of those strong momentum declines that we recently explored, and that would have us looking for more downside. The key 500 difference between stocks with extreme negative momentum and those with extreme positive momentum, however, was not quite reached. As a result, I tried a different analysis: What happens after the market, like Thursday, declines by more than 1% and closes at a five-day low?
Since the bull market began in 2003 (N = 728), we've had 55 days in which the market has dropped more than 1% and closed at a five-day low. Three days later, the market averaged a gain of .36% (35 up, 20 down), much better than the average three-day gain for the remainder of the sample (.17%; 396 up, 277 down). This finding of superior returns after X-day lows is similar to the findings from Larry Connors in his book "How Markets Really Work". Unlike strong momentum declines, which tend to persist in the short run, extended declines tend to reverse.
Wednesday, February 01, 2006
Broad Momentum Rises: What Happens Next?
Yesterday we saw that broad market declines--ones in which a large number of issues closed below the volatility envelopes surrounding their short-term moving averages--lead to further market weakness in the near term, while declines that are less broad are typically followed by reversal (as we saw in today's market).
In this analysis, we'll look at the same broad momentum variable and see if it is relevant to market rises. Since March, 2003 (N = 724), we've had 37 rising days in which the difference between the number of stocks closing above their short-term envelopes and the number of stocks closing below their envelopes has been 500 or greater. Three days later, SPY has been up by an average of .58% (27 up, 10 down). This is much stronger than the average three-day gain of .11% (207 up, 158 down) for other rising days. Indeed, when the market is up on less than broad momentum, the average three-day gain underperforms the sample overall (.18%; 430 up, 294 down).
What this suggests is that broad momentum leads to trend continuation in the short run, both to the downside and upside. Rising market days without broad momentum do not necessarily lead to market declines, but do offer subnormal returns in the near term. When markets rise on broad momentum, the moves tend to persist over the next several days.
In this analysis, we'll look at the same broad momentum variable and see if it is relevant to market rises. Since March, 2003 (N = 724), we've had 37 rising days in which the difference between the number of stocks closing above their short-term envelopes and the number of stocks closing below their envelopes has been 500 or greater. Three days later, SPY has been up by an average of .58% (27 up, 10 down). This is much stronger than the average three-day gain of .11% (207 up, 158 down) for other rising days. Indeed, when the market is up on less than broad momentum, the average three-day gain underperforms the sample overall (.18%; 430 up, 294 down).
What this suggests is that broad momentum leads to trend continuation in the short run, both to the downside and upside. Rising market days without broad momentum do not necessarily lead to market declines, but do offer subnormal returns in the near term. When markets rise on broad momentum, the moves tend to persist over the next several days.
Tuesday, January 31, 2006
Broad Momentum Decline: What Comes Next?
Yesterday we saw that slow, narrow days lead to unfavorable expectations over the near term. Sure enough, today we saw a late drop today that could turn into a broad momentum decline tomorrow. A broad momentum decline, as I'm defining it, is one in which 500 or more stocks are displaying strong downward momentum as compared with upward momentum. Momentum is measured by a price close above or below a volatility band surrounding the stock's short-term moving average. All stocks in the NYSE and NASDAQ are included. When 500 or more stocks are closing below their envelopes than above, you have a large number of issues that are very weak in the near term.
Since March, 2003 (N = 724), we have had 42 broad momentum decline days. Two days later in SPY, the market was down by an average of -.11% (16 up, 26 down). After declining market days that did not show broad market declines (N = 271), the market was up two days later by an average of .18% (158 up, 113 down). What this suggests is that markets that fall without broad momentum tend to reverse in the short run, but markets with broad momentum declines tend to continue their weakness near term. This strikes me as a pattern worth exploring over a variety of time frames. If tomorrow turns out to be a broad momentum decline, we'd expect greater near-term weakness thereafter than if selling tomorrow is more modest.
Since March, 2003 (N = 724), we have had 42 broad momentum decline days. Two days later in SPY, the market was down by an average of -.11% (16 up, 26 down). After declining market days that did not show broad market declines (N = 271), the market was up two days later by an average of .18% (158 up, 113 down). What this suggests is that markets that fall without broad momentum tend to reverse in the short run, but markets with broad momentum declines tend to continue their weakness near term. This strikes me as a pattern worth exploring over a variety of time frames. If tomorrow turns out to be a broad momentum decline, we'd expect greater near-term weakness thereafter than if selling tomorrow is more modest.
Monday, January 30, 2006
Slow, Narrow Days: What Next?
Monday was a very narrow range, slow day in SPY. Volume was approximately 60% of the 60-day average volume and the entire range for the day was only .36%. What tends to happen after such narrow, slow days?
First off, it's interesting to note that SPY volume as a % of 60-day volume correlates .51 with the daily trading range. Monitoring SPY volume in real time is an excellent way of handicapping the likely volume for the day. Seeing that volumes were running well below the normal volume for the relevant period alerted one to take profits quickly and to expect a range bound trade.
Since March, 2003 (N = 728), we've had 30 days in which the SPY range has been less than or equal to .50% and the volume has been 70% or less of the 60-day average. The average change three days later is -.43% (8 up, 22 down), much worse than the three-day average change of .19% (430 up, 298 down) for the sample overall. It appears that low volume and low volatility do not bode well for the bulls in the near term. The ratio of down to up occasions following the slow, narrow days is quite striking.
First off, it's interesting to note that SPY volume as a % of 60-day volume correlates .51 with the daily trading range. Monitoring SPY volume in real time is an excellent way of handicapping the likely volume for the day. Seeing that volumes were running well below the normal volume for the relevant period alerted one to take profits quickly and to expect a range bound trade.
Since March, 2003 (N = 728), we've had 30 days in which the SPY range has been less than or equal to .50% and the volume has been 70% or less of the 60-day average. The average change three days later is -.43% (8 up, 22 down), much worse than the three-day average change of .19% (430 up, 298 down) for the sample overall. It appears that low volume and low volatility do not bode well for the bulls in the near term. The ratio of down to up occasions following the slow, narrow days is quite striking.
Sunday, January 29, 2006
Falling Markets and Stocks Making New Lows
 This poster graces my office, thanks to Despair.com.
Yesterday's entry found that there was greater follow through to the upside when rises in SPY were accompanied by an expansion in the number of stocks making fresh 20-day highs. Today we look at days in which SPY declines to see if the number of new lows makes a difference.
Since January, 2003, we have had 334 declining days in SPY. When those declines have been accompanied by an increase in the number of stocks registering fresh 20-day lows (N = 249), the average gain in SPY over the next two days has been .08% (133 up, 116 down). When declines in SPY have not been accompanied by an expansion in new lows (N = 85), the next two days in SPY have averaged a gain of .25% (48 up, 37 down).
When there is broad participation to the upside during market rises, there is usually room for further upside. When there is not broad participation to the downside during market declines, there tends to be reversal of the weakness. These are relationships that may well hold over other time frames as well.
Saturday, January 28, 2006
Rising Markets and Stocks Making New Highs
If you've followed the Trading Psychology Weblog, you know I place great emphasis upon whether or not rising markets expand the number of stocks making fresh short-term highs (and vice versa). Rises in ES that do not expand new highs and declines that do not expand new lows are, in my testing, more likely to reverse than rises and falls that are accompanied by broad participation across market sectors.
Going back to January, 2003, I found 419 days in which the S&P 500 Index (SPY) was up on the day. Of these, 229 displayed an expansion in the number of NYSE, NASDAQ, and AMEX stocks making new 20 day highs. Three days later, SPY was up by an average of .20% (136 up, 93 down). When the rises in SPY were not accompanied by an expansion of 20 day highs, SPY over the next three days averaged a gain of only .02% (103 up, 87 down).
It will be interesting to study this relationship over different time frames, intraday as well as longer term. In general, it appears that upside moves are more likely to continue higher if they carry a majority of issues to fresh new highs. When this doesn't happen, it suggests that many stock sectors are not participating in the rise, setting up subnormal near term returns.
Going back to January, 2003, I found 419 days in which the S&P 500 Index (SPY) was up on the day. Of these, 229 displayed an expansion in the number of NYSE, NASDAQ, and AMEX stocks making new 20 day highs. Three days later, SPY was up by an average of .20% (136 up, 93 down). When the rises in SPY were not accompanied by an expansion of 20 day highs, SPY over the next three days averaged a gain of only .02% (103 up, 87 down).
It will be interesting to study this relationship over different time frames, intraday as well as longer term. In general, it appears that upside moves are more likely to continue higher if they carry a majority of issues to fresh new highs. When this doesn't happen, it suggests that many stock sectors are not participating in the rise, setting up subnormal near term returns.
Friday, January 27, 2006
When Big Caps Outpace Small Caps
Yesterday's entry looked at occasions when small caps outperform large caps on the upside and found that such a scenario leads to short-term strength in the S&P, which indeed proved to be the case on Friday. Friday's rise, however, was notable in that the gain in the S&P (SPY) was almost twice the size of the gain in the Russell 2000 Index (IWM): .93% vs. .50%.
I examined occasions in which SPY was up more than .50% on a one-day basis, and then broke down those occasions based upon the performance of IWM. In general, since January, 2003 (N = 771), there have been 202 days in which SPY has been up more than .50%. Two days later, SPY has averaged a loss of -.04% (96 up, 106 down)--weaker than the average two-day gain of .14% for the remainder of the sample (316 up, 253 down). This fits the pattern noted often in this blog: strength leads to near-term weakness and vice versa.
When SPY is up by more than .50% in a single day and outperforms IWM (N = 66), the next three days average a loss of -.08% (29 up, 37 down). When IWM outperforms the strong SPY, the next three days average a gain of .14% (85 up, 51 down). It thus appears that underperformance by IWM worsens the subnormal returns that tend to follow strong market days. When IWM outperforms SPY, strength is more likely to lead to further strength. When SPY outperforms the small caps, strength is more likely to be reversed.
I examined occasions in which SPY was up more than .50% on a one-day basis, and then broke down those occasions based upon the performance of IWM. In general, since January, 2003 (N = 771), there have been 202 days in which SPY has been up more than .50%. Two days later, SPY has averaged a loss of -.04% (96 up, 106 down)--weaker than the average two-day gain of .14% for the remainder of the sample (316 up, 253 down). This fits the pattern noted often in this blog: strength leads to near-term weakness and vice versa.
When SPY is up by more than .50% in a single day and outperforms IWM (N = 66), the next three days average a loss of -.08% (29 up, 37 down). When IWM outperforms the strong SPY, the next three days average a gain of .14% (85 up, 51 down). It thus appears that underperformance by IWM worsens the subnormal returns that tend to follow strong market days. When IWM outperforms SPY, strength is more likely to lead to further strength. When SPY outperforms the small caps, strength is more likely to be reversed.
Thursday, January 26, 2006
Do Small Cap Stocks Lead the S&P?
A couple of readers suggested that I take a look at what happens with the S&P market as a function of strength in the small cap (Russell) stocks, given the recent outperformance of those small caps. I recently sent off an article to the Trading Markets site that should appear Friday AM that will present one facet of this issue. In this analysis, I focus on markets since January, 2003 (N = 768) in which the Russell is up on a one, two, and three day basis, with the three-day gain exceeding 2% (N = 130).
Three days later, the S&P is up by an average of .45% (87 up, 43 down), much stronger than the three-day average gain of .07% for the remainder of the sample (358 up, 280 down). A strong Russell, such as we've had lately, has led to near-term large cap stock strength. In this context, it does appear that small stocks do lead large ones during strong moves. This may be because small stocks tend to be more volatile and thus will outperform during bullish trending markets.
Three days later, the S&P is up by an average of .45% (87 up, 43 down), much stronger than the three-day average gain of .07% for the remainder of the sample (358 up, 280 down). A strong Russell, such as we've had lately, has led to near-term large cap stock strength. In this context, it does appear that small stocks do lead large ones during strong moves. This may be because small stocks tend to be more volatile and thus will outperform during bullish trending markets.
Wednesday, January 25, 2006
Range Bound Volatile Day
How much territory does a market cover in a day? I decided to add up all the one minute ranges in ES from 11/1/05 - present (N = 57 days). It turns out that the average total movement of the ES per day is 217 points, with an average daily range of 9.9 points. Today, the market traveled a total of 304 points, the second highest total in the sample. The only higher day was Friday's big move down, which came in at 307 points. Friday's range, however, was 23.75 points--fully 10 more points than yesterday's range. Friday was a volatile trend day, but today was a volatile, non-trending day. Indeed, when we look at past days with an approximate 13 point range, the average number of points traveled is under 230--well below today's total. I could only find three days in the sample in which we had a somewhat similar configuration of a moderately wide range and very large movement within that range. All three led to a relatively non-volatile market the following day, with ranges below 10 points.
This will bear further study. What we're seeing is that volatility--as defined by total range during a day is not the same as volatility defined as the total movement within that day. Although the two correlate highly--about .60--it means that only 36% of the variance in a day's range is accounted for by the size of minute-to-minute movement. High volatility range bound days may not have the same expectations as high volatility trend days, both with respect to directional follow through and carry over of volatility. My initial findings suggest that institutional participation is higher during the trend days, creating greater price and volatility persistence. I hope to post further results in the near future.
This will bear further study. What we're seeing is that volatility--as defined by total range during a day is not the same as volatility defined as the total movement within that day. Although the two correlate highly--about .60--it means that only 36% of the variance in a day's range is accounted for by the size of minute-to-minute movement. High volatility range bound days may not have the same expectations as high volatility trend days, both with respect to directional follow through and carry over of volatility. My initial findings suggest that institutional participation is higher during the trend days, creating greater price and volatility persistence. I hope to post further results in the near future.
Tuesday, January 24, 2006
Is Google a Bellwether?
Note: My personal site will be adding additional information re: my volatility research and will be updating over the next few days.
Google's dramatic decline on Friday was followed by two solid gains on Monday and Tuesday, leaving GOOG up over 10% thus far this week. That led me to ask the question: How good of a bellwether is GOOG when it is up or down sharply in the short-term?
Going back to August, 2004 (N = 353), we find 30 days in which GOOG has shown a gain of over 5% in a two day period. Three days later, the S&P 500 Index (SPY) is up by an average .56% (20 up, 10 down). This is quite a bit better than the average two-day gain of .12% (206 up, 147 down) for the sample overall.
I also found 21 days in which GOOG was down by 4% or more over a two-day period. Five days later, SPY was up by an average .96%, with an amazing 19 occasions up, 2 down. This is quite a bit better than the average five-day change of .20% (208 up, 145 down) for the sample overall.
Interestingly, the near-term outlook is good for SPY when GOOG is very strong and when it's very weak. Score this one for the bulls with respect to the current market. (Note: Other factors lead me to be concerned about the present market's upside potential; I will outline those on my site tonight). When GOOG is strong, it means that the market's speculative sentiment is alive, and that carries over to near-term market trade. When GOOG sells off strongly, speculative froth is exiting the marketplace, and that puts in a short-term market bottom. Such may have been the case on Friday.
Of course, all speculative leaders end up eventually becoming laggards, so these patterns can't continue forever. In this bull market so far, however, GOOG has been a worthy bellwether.
Keep an eye on the Trading Markets site: I hope to extend the GOOG research in an article.
Google's dramatic decline on Friday was followed by two solid gains on Monday and Tuesday, leaving GOOG up over 10% thus far this week. That led me to ask the question: How good of a bellwether is GOOG when it is up or down sharply in the short-term?
Going back to August, 2004 (N = 353), we find 30 days in which GOOG has shown a gain of over 5% in a two day period. Three days later, the S&P 500 Index (SPY) is up by an average .56% (20 up, 10 down). This is quite a bit better than the average two-day gain of .12% (206 up, 147 down) for the sample overall.
I also found 21 days in which GOOG was down by 4% or more over a two-day period. Five days later, SPY was up by an average .96%, with an amazing 19 occasions up, 2 down. This is quite a bit better than the average five-day change of .20% (208 up, 145 down) for the sample overall.
Interestingly, the near-term outlook is good for SPY when GOOG is very strong and when it's very weak. Score this one for the bulls with respect to the current market. (Note: Other factors lead me to be concerned about the present market's upside potential; I will outline those on my site tonight). When GOOG is strong, it means that the market's speculative sentiment is alive, and that carries over to near-term market trade. When GOOG sells off strongly, speculative froth is exiting the marketplace, and that puts in a short-term market bottom. Such may have been the case on Friday.
Of course, all speculative leaders end up eventually becoming laggards, so these patterns can't continue forever. In this bull market so far, however, GOOG has been a worthy bellwether.
Keep an eye on the Trading Markets site: I hope to extend the GOOG research in an article.
Monday, January 23, 2006
Narrow Bounce After a Big Decline: A Rare Occurrence

I couldn't wait to add this to the blog. Check my personal site tomorrow for details. This is a measure of institutional presence in the market that updates every 20 seconds. It correlates with daily price range by .45 since the beginning of January. Now the question is whether institutional involvement during period X will predict volatility in period Y. Stay tuned...this is getting fun.
I have received a number of email inquiries regarding indicators for assessing the likely volatility of the coming day's trade. I will post something to my personal site shortly on this topic. Obviously such information is invaluable on days such as Monday, when all indications from Friday pointed to likely volatility. When we saw the narrow overnight range, however, followed by mediocre volume in the ES, it became clear that this was not going to be a breakout day. Being able to evaluate volatility in real time is critical, because it enables you to handicap the odds of moves breaking through ranges vs. reversing back into the ranges. As we can see from the comparison of Friday and Monday, greater volume and volatility makes the difference between a day of breakouts and a range bound day.
We followed Friday's large decline with a small gain amidst low volatility on Monday. As we saw from the previous posts, this is a statistically unusual event. When I went back to December, 1998 (N = 1793), I found how unusual this is. After a large decline of more than 1.5%, we have never--until Monday--had a rise on such low volatility. For what it's worth, small bounces from large declines that occurred on ranges of less than 1.5% (N = 8) were down the next day on six of those occasions for an average loss of -.94%. In general, lower volatility bounces tended to fare more poorly three days out than high volatility rises. While the numbers are too small for statistical significance, their bearish cast makes sense given that--thus far--the downside is attracting more interest than the upside and--in Market Profile terms--we are accepting value at progressively lower prices.
Sunday, January 22, 2006
One More Perspective on Steep Declines
Note: I recently submitted an article to Trading Markets regarding the recent downward volatile trade. That should appear Monday AM. Also see the last couple of entries on this site for a perspective on the week to come. Finally, Sunday evening's Trader Performance blog on my personal site will offer some psychological insight as to how to utilize the historical analyses offered herein.
For my last analysis of Friday's sizable decline, I took a different approach. Going back to January, 2000 (N = 1518), I calculated the 200 day standard deviation of price changes and investigated what happens after the market moves more than 2 standard deviations lower in a single day. The beauty of this analysis is that it adjusts the investigation for changes in volatility over time, so that what is steep in a non-volatile market and in a volatile one is different.
I found 34 such occasions and looked at what happens in SPY afterward. Two days after the steep drop, the market was up 23 times, down 11 for an average gain of .77%. This is much stronger than the average two-day gain of .00% for the sample overall (759 up, 759 down). Steep drops tend to be followed by rebounds in the near term. Buying weakness the day after the steep drop and holding for strength the following day was a profitable strategy overall.
That having been said, the strategy was much less successful for much of 2001 and 2002 than for the rest of the sample. As we saw before, weakness in a bull market provides opportunity; in a bear market it often leads to a cascade of selling and a clustering of weak days. This clustering, such as we saw in July, 2002, is the reason why such weak market occasions must be followed by careful reading of subsequent real-time action. Although the odds are bullish following weak market days overall, when weakness does follow weakness, the downside can be substantial--especially given the enhanced volatility that such big down days engender.
Since the bull market started in 2003, we have had 7 instances of weak market days that have fallen more than two standard deviations. The market has been up 5 times, down twice, for an average two-day gain of .85%. Once again, the response of the market to the latest weakness will provide a piece of information regarding whether we continue in the bull mode.
For my last analysis of Friday's sizable decline, I took a different approach. Going back to January, 2000 (N = 1518), I calculated the 200 day standard deviation of price changes and investigated what happens after the market moves more than 2 standard deviations lower in a single day. The beauty of this analysis is that it adjusts the investigation for changes in volatility over time, so that what is steep in a non-volatile market and in a volatile one is different.
I found 34 such occasions and looked at what happens in SPY afterward. Two days after the steep drop, the market was up 23 times, down 11 for an average gain of .77%. This is much stronger than the average two-day gain of .00% for the sample overall (759 up, 759 down). Steep drops tend to be followed by rebounds in the near term. Buying weakness the day after the steep drop and holding for strength the following day was a profitable strategy overall.
That having been said, the strategy was much less successful for much of 2001 and 2002 than for the rest of the sample. As we saw before, weakness in a bull market provides opportunity; in a bear market it often leads to a cascade of selling and a clustering of weak days. This clustering, such as we saw in July, 2002, is the reason why such weak market occasions must be followed by careful reading of subsequent real-time action. Although the odds are bullish following weak market days overall, when weakness does follow weakness, the downside can be substantial--especially given the enhanced volatility that such big down days engender.
Since the bull market started in 2003, we have had 7 instances of weak market days that have fallen more than two standard deviations. The market has been up 5 times, down twice, for an average two-day gain of .85%. Once again, the response of the market to the latest weakness will provide a piece of information regarding whether we continue in the bull mode.
Saturday, January 21, 2006
High Volume Steep Declines: A Closer Look
I took a more detailed look at what happens after high volume large declines, and the findings are interesting. Since January, 1998 (N = 2021), I found 36 occasions in SPY in which we had a decline of greater than 1.5% on volume that exceeds the average 60 day daily volume by more than 75%. This fits Friday's trade well, where we declined by 1.82% on 105% of the average 60 day volume.
From the close to the following day's open, the average loss was -.12% (18 up, 18 down), which is weaker than the average move to open of .04% (1104 up, 917 down). Nine of the 36 occasions moved more than 1% up or down from close to open, far more often than normally occurs. This is reflective of above average overnight volatility following the high volume decline.
This above average volatility carries over to the next trading day as well. The average high to low range for the sample overall is 1.60%. For the day after the high volume down day, however, the average trading range has been 3.2%. Indeed, only 4 of the 36 occasions saw a high to low range of under 1.5%. Clearly this leads us to expect some volatile trade on Monday.
In terms of directional edge, although the day after the weak high volume day tends to open weak, by the close this has typically turned around. Three days after the weak high volume day, the market is up by an average .54% (23 up, 13 down), much better than the average three-day gain of .06% (1091 up, 930 down). When we break this down historically, though, a pattern emerges: since 2001, the results following a weak high volume decline have been much worse than from 1998-2000. During the bull market of 1998-2000, weak high volume declines tended to be followed by gains; during the bear market, those same declines tended to cluster, creating multiple high volume declines and subnormal results. For instance, from 2001 - 2005, two days after the high volume large decline we averaged a drop of -.84% (6 up, 12 down), but from 1998 - 2000 we averaged a gain of 1.64% (15 up, 3 down)!
Where does that leave us? The clearest finding from the data is that a high volume weak day tends to produce high volatility prior to the open (overnight session) and during the next day's trade. In a bull market, such declines become short-term opportunities to pick up bargains. In bear markets, such declines feed upon themselves, generating large price drops. How the market responds to Friday will tell us much about the kind of market we're in. I will be monitoring the measures of buying/selling from the Trading Psychology Weblog intraday to gauge whether we're seeing bargain hunting or panic selling.
FWIW, since 2003, we've only had 3 days of large declines on high volume. The next day, the market has been down twice, up once. When we opened lower on those two occasions, we traded lower through the remainder of the day. When we opened higher, we traded modestly lower from open to close. I will need to see tangible evidence of buying before fishing for bargains in Monday's trade.
On a separate note, if you're looking for a light moment, check out my site and you'll see the first article I've ever written for a website to be outright turned down. I can't figure out why...
From the close to the following day's open, the average loss was -.12% (18 up, 18 down), which is weaker than the average move to open of .04% (1104 up, 917 down). Nine of the 36 occasions moved more than 1% up or down from close to open, far more often than normally occurs. This is reflective of above average overnight volatility following the high volume decline.
This above average volatility carries over to the next trading day as well. The average high to low range for the sample overall is 1.60%. For the day after the high volume down day, however, the average trading range has been 3.2%. Indeed, only 4 of the 36 occasions saw a high to low range of under 1.5%. Clearly this leads us to expect some volatile trade on Monday.
In terms of directional edge, although the day after the weak high volume day tends to open weak, by the close this has typically turned around. Three days after the weak high volume day, the market is up by an average .54% (23 up, 13 down), much better than the average three-day gain of .06% (1091 up, 930 down). When we break this down historically, though, a pattern emerges: since 2001, the results following a weak high volume decline have been much worse than from 1998-2000. During the bull market of 1998-2000, weak high volume declines tended to be followed by gains; during the bear market, those same declines tended to cluster, creating multiple high volume declines and subnormal results. For instance, from 2001 - 2005, two days after the high volume large decline we averaged a drop of -.84% (6 up, 12 down), but from 1998 - 2000 we averaged a gain of 1.64% (15 up, 3 down)!
Where does that leave us? The clearest finding from the data is that a high volume weak day tends to produce high volatility prior to the open (overnight session) and during the next day's trade. In a bull market, such declines become short-term opportunities to pick up bargains. In bear markets, such declines feed upon themselves, generating large price drops. How the market responds to Friday will tell us much about the kind of market we're in. I will be monitoring the measures of buying/selling from the Trading Psychology Weblog intraday to gauge whether we're seeing bargain hunting or panic selling.
FWIW, since 2003, we've only had 3 days of large declines on high volume. The next day, the market has been down twice, up once. When we opened lower on those two occasions, we traded lower through the remainder of the day. When we opened higher, we traded modestly lower from open to close. I will need to see tangible evidence of buying before fishing for bargains in Monday's trade.
On a separate note, if you're looking for a light moment, check out my site and you'll see the first article I've ever written for a website to be outright turned down. I can't figure out why...
Friday, January 20, 2006
High Volume Steep Decline: What Comes Next
Friday's market moved sharply lower, with SPY down 1.82% on volume that was 136% of its 20 day average volume. What typically happens after such a decline? I will provide a preliminary analysis here, but will follow up tomorrow with further analyses.
I went all the way back to January, 1998 (N = 2022 trading days) and found only 29 days in SPY that were down more than 1.5% on volume that exceeded the 20 day average by more than 75%. Large, high volume declines have thus been rare--especially recently. During this low volatility bull market, we've only had one occurrence: 3/10/04. The market followed that down day with a further decline of 1.3% the next trading day.
Over the next three trading days, when we've had a steep decline on large volume (N = 29), the market has been up 19 times, down 10 for an average gain of .83%. That is quite a bit better than the average three-day gain of .06% (1091 up, 931 down) for the sample overall. There is thus a tendency to rebound over the near term.
Interestingly, the day after a high volume steep decline tends to be a big day, whether up or down. Of the 29 occurrences, 19 were either up or down the next day by more than a full percent, and 8 of the 29 moved more than 2%. This reflects serial volatility: highly volatile trading days tend to be followed by days that are above average in volatility. In fact, the average absolute one day change in the sample was .92%, but the absolute one day change following a high volume steep decline was 1.56%.
More to follow...
I went all the way back to January, 1998 (N = 2022 trading days) and found only 29 days in SPY that were down more than 1.5% on volume that exceeded the 20 day average by more than 75%. Large, high volume declines have thus been rare--especially recently. During this low volatility bull market, we've only had one occurrence: 3/10/04. The market followed that down day with a further decline of 1.3% the next trading day.
Over the next three trading days, when we've had a steep decline on large volume (N = 29), the market has been up 19 times, down 10 for an average gain of .83%. That is quite a bit better than the average three-day gain of .06% (1091 up, 931 down) for the sample overall. There is thus a tendency to rebound over the near term.
Interestingly, the day after a high volume steep decline tends to be a big day, whether up or down. Of the 29 occurrences, 19 were either up or down the next day by more than a full percent, and 8 of the 29 moved more than 2%. This reflects serial volatility: highly volatile trading days tend to be followed by days that are above average in volatility. In fact, the average absolute one day change in the sample was .92%, but the absolute one day change following a high volume steep decline was 1.56%.
More to follow...
Thursday, January 19, 2006
Overnight Moves and Next Day Volatility
I recently submitted an article to Trading Markets that looks at the relationship between the size of the overnight moves in the major indices and the trading range the next trading session. It turns out that for such averages as the S&P 500 Index (SPY), the NASDAQ 100 Index (QQQQ), and the Dow Jones Industrial Average (DIA), the correlation between the size of their move from close to open and the subsequent high-low range is in the order of .33. When the overnight move is greater than .50%, the market has a trading range that exceeds 1% over three-quarters of the time. When the overnight move is less than .05%, the market trades in a range greater than 1% less than half of the time.
Interestingly, the Russell 2000 correlation is only about half that of the Dow. Overnight events may well impact large cap issues more than small caps. It is also interesting to look at correlations for individual stocks. Many stocks, such as MSFT (.30), AAPL (.27), and IBM (.23) have correlations similar to the indices. Others, such as XOM (.07) show little relationship between the magnitude of overnight moves and trading range the next day. This may be because XOM is impacted more by contemporaneous movement in the oil market than by overnight events.
Using overnight movement and current volume to predict near-term volatility has been extremely helpful in my trading, as volatility is a predictor of whether markets will break out of ranges vs. revert to mean trading prices. This appears to be a strategy that can work for individual equities as well as indices.
Interestingly, the Russell 2000 correlation is only about half that of the Dow. Overnight events may well impact large cap issues more than small caps. It is also interesting to look at correlations for individual stocks. Many stocks, such as MSFT (.30), AAPL (.27), and IBM (.23) have correlations similar to the indices. Others, such as XOM (.07) show little relationship between the magnitude of overnight moves and trading range the next day. This may be because XOM is impacted more by contemporaneous movement in the oil market than by overnight events.
Using overnight movement and current volume to predict near-term volatility has been extremely helpful in my trading, as volatility is a predictor of whether markets will break out of ranges vs. revert to mean trading prices. This appears to be a strategy that can work for individual equities as well as indices.
Wednesday, January 18, 2006
Strength After a Down Open: What Has Followed
Wednesday's market opened down, but was up from open to close. Since January, 2004 (N = 514), we've had 52 occasions in which the market (SPY) opened lower by .3% or more. The next day, the market was up by an average of .02% (31 up, 21 down)--no real edge relative to the average change of .03% (283 up, 231 down) for the sample overall.
When we use a median split to divide the days that opened down by whether they were strong vs. weak from open to close, a pattern emerges. When the market was strong from open to close after a down open (N = 26), the next day averaged a loss of -.20% (12 up, 14 down). When the market was weak from open to close after a down open (N = 26), the next day averaged a gain of .23% (19 up, 7 down).
Interestingly, strength during the day after a weak open has not carried over to the next day. Indeed, more often than not, such strength has been reversed.
When we use a median split to divide the days that opened down by whether they were strong vs. weak from open to close, a pattern emerges. When the market was strong from open to close after a down open (N = 26), the next day averaged a loss of -.20% (12 up, 14 down). When the market was weak from open to close after a down open (N = 26), the next day averaged a gain of .23% (19 up, 7 down).
Interestingly, strength during the day after a weak open has not carried over to the next day. Indeed, more often than not, such strength has been reversed.
Tuesday, January 17, 2006
Double Down: What Next?
Today's market gapped lower at the open and closed lower. Now it appears likely that we'll gap lower tomorrow AM on the NASDAQ 100 Index (QQQQ), given the weak Intel news. What has happened during the trading day after we've gapped lower two days in a row?
Since January, 2003 (N = 765), we've only had 1o occasions in which a day that has closed lower and gapped down at the open has been followed by a second gap down. From the open of the market that second day (which would correspond to Wednesday in current trade) to the close, the market averaged a loss of -.74% (2 up, 8 down). That's quite a bit more bearish than the average open to close change of .01% (393 up, 373 down) for the sample overall.
In short, despite the market's tendency to reverse weakness in the short run, two consecutive gaps down have not, on average, led to a rebound during the subsequent trading day. Although it might be tempting to jump into the market at the open and look for bargains, on average this has not been a winning strategy since 2003.
Since January, 2003 (N = 765), we've only had 1o occasions in which a day that has closed lower and gapped down at the open has been followed by a second gap down. From the open of the market that second day (which would correspond to Wednesday in current trade) to the close, the market averaged a loss of -.74% (2 up, 8 down). That's quite a bit more bearish than the average open to close change of .01% (393 up, 373 down) for the sample overall.
In short, despite the market's tendency to reverse weakness in the short run, two consecutive gaps down have not, on average, led to a rebound during the subsequent trading day. Although it might be tempting to jump into the market at the open and look for bargains, on average this has not been a winning strategy since 2003.
Monday, January 16, 2006
Bonds and Stocks: The Longer View
As we found earlier, bond and stock prices have been positively correlated over longer time frames in the market (40 days) since 2003, but not on a day-to-day basis. We saw with day-to-day results, strong bonds and strong stocks led to subnormal returns; weak bonds and weak stocks led to above average returns.
Now we'll look at stocks and bonds over a 40-day basis. Specifically, we want to see if strong bonds over a 40 day period are associated with strong stocks over the next 40 days. Since March, 2003 (N = 686), 40-day periods have had a distinctly positive bias. The S&P 500 Index has averaged a gain of 2.33% (483 periods up, 203 down) during that time. When we conduct a median split of the data based on 40-day bond strength, we find that strong bonds yield an average gain of 3.30% in SPX over the next 40 days (260 up, 83 down). When bonds are weak, the next 40 days in SPX average 1.35% (223 up, 120 down).
What we're seeing is a very different pattern in the short-term and longer-term data. For intermediate-term traders and for investors, bond strength is bullish for stocks. For short-term traders, bond strength has been bearish for stocks. Knowing one's time frame and price patterns typical of one's price frame is all-important.
Now we'll look at stocks and bonds over a 40-day basis. Specifically, we want to see if strong bonds over a 40 day period are associated with strong stocks over the next 40 days. Since March, 2003 (N = 686), 40-day periods have had a distinctly positive bias. The S&P 500 Index has averaged a gain of 2.33% (483 periods up, 203 down) during that time. When we conduct a median split of the data based on 40-day bond strength, we find that strong bonds yield an average gain of 3.30% in SPX over the next 40 days (260 up, 83 down). When bonds are weak, the next 40 days in SPX average 1.35% (223 up, 120 down).
What we're seeing is a very different pattern in the short-term and longer-term data. For intermediate-term traders and for investors, bond strength is bullish for stocks. For short-term traders, bond strength has been bearish for stocks. Knowing one's time frame and price patterns typical of one's price frame is all-important.
Sunday, January 15, 2006
Weak Stocks and Bonds - Continuing the Investigation
Yesterday's entry looked at strong days in the stocks since 2003 and found a tendency for near-term reversal, especially when bonds were also strong. That made me curious about weak days in stocks (SPX). Is the outlook following weakness different as a function of bond prices?
Since January, 2003 (N = 760), we've had 185 days in which SPX has been down by half a percent or more. The next day, stocks have risen on average .12% (112 up, 73 down), which is considerably stronger than the average rise of .03% for the remainder of the sample (310 up, 265 down). This is the pattern of strength following weakness that we've encountered before.
Once again I subjected the weak SPX days to a median split based upon bond price performance that day. When bonds were weak and stocks were weak (N = 93), the next day in stocks averaged a gain of .26% (62 up, 31 down). When bonds were strong and stocks were weak (N = 92), the next day in stocks averaged a loss of -.02% (50 up, 42 down). Again, this is counterintuitive. You would think that falling stocks and rising interest rates (falling bond prices) would yield weak stocks going forward. Just the opposite is the case: when stocks have been strong and bonds strong, we've had subnormal short-term returns going forward. When stocks have been weak and bonds weak, we've had above average short-term returns.
These patterns will be worth following, especially given the recent divergence between stocks (which have made new highs) and bonds (which have not).
Since January, 2003 (N = 760), we've had 185 days in which SPX has been down by half a percent or more. The next day, stocks have risen on average .12% (112 up, 73 down), which is considerably stronger than the average rise of .03% for the remainder of the sample (310 up, 265 down). This is the pattern of strength following weakness that we've encountered before.
Once again I subjected the weak SPX days to a median split based upon bond price performance that day. When bonds were weak and stocks were weak (N = 93), the next day in stocks averaged a gain of .26% (62 up, 31 down). When bonds were strong and stocks were weak (N = 92), the next day in stocks averaged a loss of -.02% (50 up, 42 down). Again, this is counterintuitive. You would think that falling stocks and rising interest rates (falling bond prices) would yield weak stocks going forward. Just the opposite is the case: when stocks have been strong and bonds strong, we've had subnormal short-term returns going forward. When stocks have been weak and bonds weak, we've had above average short-term returns.
These patterns will be worth following, especially given the recent divergence between stocks (which have made new highs) and bonds (which have not).
Saturday, January 14, 2006
Strong Stocks: Do Bonds Make a Difference?
Today's entry on the Trading Psychology Weblog mentioned an interesting relationship between bonds and stocks from 2003 to the present. Of the twenty days that were strongest in stocks (SPX), sixteen of those exhibited declining bond prices. Of the twenty weakest days in stocks, thirteen showed rising bond prices. It appears to be a kind of flight from/to quality phenomenon: When stocks drop, money goes into fixed income and vice versa.
This led me to wonder if we might see different expectations when strong and weak days in stocks are accompanied by strength or weakness among bonds. Since 2003 (N = 760), we had 195 days in which SPX was up by .50% or more. The next two days, the market averaged a loss of -.10% (96 up; 99 down), much worse than the .17% average gain (311 up, 254 down) in the rest of the sample. This is the weakness following strength pattern that we've noticed before.
Now, however, let's conduct a median split and compare strong SPX/strong bond days to strong SPX/weak bond days. After the strong SPX/strong bond days (N = 98), the market averaged a two-day loss of -.23% (46 up, 52 down). After the strong SPX/weak bond days (N = 97), the market averaged a two-day gain of .02% (50 up, 47 down). Interestingly, days in which both stocks and bonds are strong have been followed by noteworthy two-day weakness.
To the extent that fixed income might serve as an alternative to stocks, a rally in both stocks and bonds would represent general optimism regarding financial assets and a putting of money to work in those sectors. When stocks are strong but bonds weak, we might be seeing a mere transfer of assets within the universe of financial instruments. When traders are overly optimistic about the financials, stocks have tended to correct over the short term. Ironically, a market rally on lower interest rates--a seemingly positive development--has led to subnormal returns near term. Tomorrow I'll look at SPX weakness vis a vis bonds.
This led me to wonder if we might see different expectations when strong and weak days in stocks are accompanied by strength or weakness among bonds. Since 2003 (N = 760), we had 195 days in which SPX was up by .50% or more. The next two days, the market averaged a loss of -.10% (96 up; 99 down), much worse than the .17% average gain (311 up, 254 down) in the rest of the sample. This is the weakness following strength pattern that we've noticed before.
Now, however, let's conduct a median split and compare strong SPX/strong bond days to strong SPX/weak bond days. After the strong SPX/strong bond days (N = 98), the market averaged a two-day loss of -.23% (46 up, 52 down). After the strong SPX/weak bond days (N = 97), the market averaged a two-day gain of .02% (50 up, 47 down). Interestingly, days in which both stocks and bonds are strong have been followed by noteworthy two-day weakness.
To the extent that fixed income might serve as an alternative to stocks, a rally in both stocks and bonds would represent general optimism regarding financial assets and a putting of money to work in those sectors. When stocks are strong but bonds weak, we might be seeing a mere transfer of assets within the universe of financial instruments. When traders are overly optimistic about the financials, stocks have tended to correct over the short term. Ironically, a market rally on lower interest rates--a seemingly positive development--has led to subnormal returns near term. Tomorrow I'll look at SPX weakness vis a vis bonds.
Friday, January 13, 2006
Bonds and Stocks - Interesting Relationship
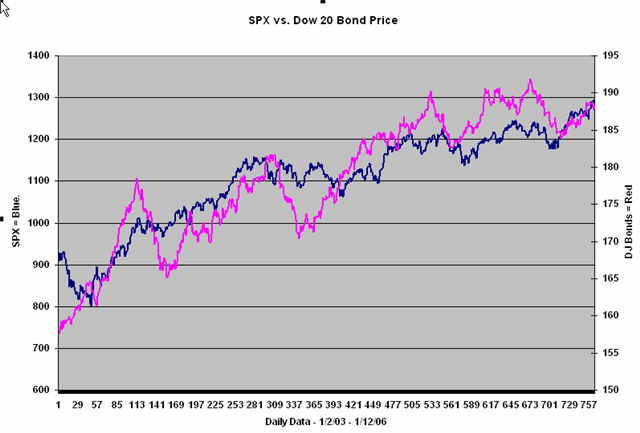
A reader suggested to me that I take a multidimensional approach to historical patterns and investigate intermarket relationships such as between bonds and stocks. This is an excellent suggestion, and it highlights the need to look at many patterns before jumping in and trading any single one. An approach I like to take is to look at non-overlapping patterns (such as between daily SP and bonds, daily SP and advance-decline, and weekly SP and volume) and see if there is a consensus among the "committee of experts". Some excellent trade ideas emerge when you see a pattern edge from multiple patterns.
The bond/stock relationship is a complicated one. As we can see from the chart above, which covers 2003 - present, the price of the DJ corporate bonds is highly correlated with the price of the S&P 500 Index. When we look on a day to day basis, however, the correlation is -.12! A strong or weak day in bonds tells us very little about whether that day was strong or weak in stocks. Over a period of 40 days, however, the correlation is .38--positive and significant.
Note that dips in bond price have been excellent points to purchase stocks. But note also that the current price highs are the first ones since 2003 to go unconfirmed by the bonds. To the extent that bonds lead stocks, there might be a message there. I will investigate this further and post tomorrow.
Thursday, January 12, 2006
Ten Days After the Runup
I just submitted an article to Trading Markets that should appear tomorrow. It takes a look at occasions since March, 2003 when we've had 1400+ new 65-day highs. Monday was our most recent occasion with over 1400 new 65-day highs, so the analysis has some current relevance. Specifically, I looked at what happens within a 10 days period following the surge in new highs: the maximum gain, maximum loss, and average price change.
Interestingly, half of the occasions (N = 26) occurred early in the bull market; half came later. The early occasions led to significant strength over the next ten days, with an average gain of 1.77% (10 up, 3 down). The later occasions were underperformers, with an average gain of .11% (7 up, 6 down). For the entire data sample (N = 703), the average ten-day price change was .63% (437 up, 265 down, 1 unchanged).
My speculation is that there is a developmental course to bull markets. Early on, strength begets strength during the swiftest portion of the market's ascent. As the rate of change slows and the market tops out later in the bull period, strength begets subnormal performance. My data suggest that the recent periods of market strength have not led to above average market declines. Rather, they've been followed by subnormal strength.
How we follow up the early strength in 2006 may say quite a bit about the relative youth vs. aging of this bull market.
BTW, the new high/low data and a very broad measure of market momentum called Demand/Supply are published daily on my personal site.
Interestingly, half of the occasions (N = 26) occurred early in the bull market; half came later. The early occasions led to significant strength over the next ten days, with an average gain of 1.77% (10 up, 3 down). The later occasions were underperformers, with an average gain of .11% (7 up, 6 down). For the entire data sample (N = 703), the average ten-day price change was .63% (437 up, 265 down, 1 unchanged).
My speculation is that there is a developmental course to bull markets. Early on, strength begets strength during the swiftest portion of the market's ascent. As the rate of change slows and the market tops out later in the bull period, strength begets subnormal performance. My data suggest that the recent periods of market strength have not led to above average market declines. Rather, they've been followed by subnormal strength.
How we follow up the early strength in 2006 may say quite a bit about the relative youth vs. aging of this bull market.
BTW, the new high/low data and a very broad measure of market momentum called Demand/Supply are published daily on my personal site.
Wednesday, January 11, 2006
Seven Straight Strong Days: QQQQ
The QQQQ (NASDAQ 100 Index) has been up for seven consecutive sessions for a total gain of 6.9%. Moreover, each of the seven days has closed nearer to its high than to its low for the day. I went back to March, 2003 (N = 703) to see what happens after such a period of strength. For the sample overall, the next seven days average a gain of .58% (406 up, 297 down). For the 47 occasions in which QQQQ has risen more than 5% over a seven-day period, the next seven days have averaged a gain of .43% (29 up, 18 down). Clearly, seven-day strength in QQQQ has not provided a bullish edge over the next seven days; nor has it been bearish.
I then looked at seven-day strong periods in QQQQ where six or more of the days closed closer to their highs than to their lows (N = 22). The next seven days averaged a gain of .28% (14 up, 8 down). Interestingly, we've only had six occasions in which all seven days during a strong period closed strong; the next seven days averaged a loss of -1.62% (3 up, 4 down).
In short, seven day strength in QQQQ has not given us further upside momentum over the next seven days. Indeed, the strongest closing seven day periods have had somewhat weaker results over the next seven days compared to the periods with fewer days closing strong.
I then looked at seven-day strong periods in QQQQ where six or more of the days closed closer to their highs than to their lows (N = 22). The next seven days averaged a gain of .28% (14 up, 8 down). Interestingly, we've only had six occasions in which all seven days during a strong period closed strong; the next seven days averaged a loss of -1.62% (3 up, 4 down).
In short, seven day strength in QQQQ has not given us further upside momentum over the next seven days. Indeed, the strongest closing seven day periods have had somewhat weaker results over the next seven days compared to the periods with fewer days closing strong.
Tuesday, January 10, 2006
Down At The Open; Up By the Close
Tuesday's market opened lower, but closed higher by almost .40% on SPY. Going back to January, 2003 (N = 761), we have 122 occasions in which the market has opened lower but rose more than .3% from open to close. Although this would seem to indicate market strength, there is no distinct edge going forward. Indeed, the reversal days slightly underperformed other days with respect to next day performance. After the reversal days, the market was down by -.06% (60 up, 62 down) the next day. The remainder of the days in the sample were up by the next day by an average .07% (363 up, 276 down). It will be interesting to test longer-term reversal patterns to see if they sport any advantage.
Monday, January 09, 2006
Broad Strength: What Next?
Intermediate-term new highs were very strong on Friday, with 2132 new 20-day highs and 1231 new 65-day highs. Since January, 2003 (N = 743), we've had 30 days where new 20-day highs were greater than 2000 and new 65-day highs were above 1000. Three days later in SPY, the market was up 15 times, down 15 for an average loss of .00%. This compares unfavorably with the average gain of .15% (421 up, 292 down) for the remainder of the sample. This relative weakness is not present 10 days out.
In short, after very broad strength, the market more often than not has consolidated over the next three days before resuming its upward course.
In short, after very broad strength, the market more often than not has consolidated over the next three days before resuming its upward course.
Sunday, January 08, 2006
One Day Rises: No Momentum Effects
So far, we've seen momentum effects over the long-term (1000-day periods) and intermediate term (10-day), in which strength begets further strength. Interestingly, however, that pattern does not apply to a day-by-day market analysis. Going back to January, 2003 (N = 759), I found 302 days in which SPY closed higher than the day previous and made a higher price high. The following day, the market's high averaged .49% above its previous day's close and averaged .00% from the previous close to the following day's close. This is weaker than the average .59% from close to next day's high for the sample overall and the average gain of .05% day over day. When I conducted median splits, the strength of the day's rise had no significant impact on the strength of the next trading day. Indeed, strong days--if anything--tend to invite profit taking, not follow through strength. This is but one more example of where it's tempting to generalize patterns from one time frame to another--but perilous to do so.
Saturday, January 07, 2006
Ten-Day Highs: Evidence of Momentum Effects
Yesterday's post found momentum effects with respect to multi-year highs. When we make longer-term highs in a strongly rising market, expectations for gains going forward are better than when we make longer-term highs in a modest uptrend. I decided to explore this as a general pattern by seeing what happens after we make 10-day highs, as was the case Friday. Interestingly, although the market has seemed strong over the past ten days, it is below the average gain of 2.52% that we have normally seen during 10-day highs since 2003.
Looking at SPY since January, 2003 (N = 750), we find that 176 instances of ten-day highs. Three days later, the market is up by an average of .01% (94 up, 82 down), worse than the average three-day gain of .14% (437 up, 313 down) for the sample overall. A median split of the 10-day highs, however, once again shows a momentum effect. When the new highs are made in a strong market, the next three days average a gain of .10% (54 up, 34 down), but when new highs are made in a weaker market, the next three days average a loss of -.08% (40 up, 48 down).
This suggests that the present market does not have an edge relative to historical averages with respect to the next three days and may even be at a disadvantage. Markets that make 10 day highs but show 10-day rates of change of less than 2% have underperformed those that make 10 day highs with stronger momentum.
Looking at SPY since January, 2003 (N = 750), we find that 176 instances of ten-day highs. Three days later, the market is up by an average of .01% (94 up, 82 down), worse than the average three-day gain of .14% (437 up, 313 down) for the sample overall. A median split of the 10-day highs, however, once again shows a momentum effect. When the new highs are made in a strong market, the next three days average a gain of .10% (54 up, 34 down), but when new highs are made in a weaker market, the next three days average a loss of -.08% (40 up, 48 down).
This suggests that the present market does not have an edge relative to historical averages with respect to the next three days and may even be at a disadvantage. Markets that make 10 day highs but show 10-day rates of change of less than 2% have underperformed those that make 10 day highs with stronger momentum.
Friday, January 06, 2006
Multi-Year Highs: A Longer-Term Perspective
We've been hearing so much about the Dow and other stock indices making multi-year highs that I decided to take a longer look and see what happens after we make a 1000 day high in the Dow. This roughly corresponds to a 3-4 year price high. I went back to July, 1952 (N = 13362) and found 889 occasions of 1000-day highs. Eighty days later, the Dow was up by an average of 3.13% (633 up, 256 down), somewhat more favorable than the average eighty-day gain for the sample: 2.56% (8535 up, 4827 down).
Interestingly, however, when we look at how much the Dow has actually risen during the 1000 day period in which it made new price highs, the forecast for the next eighty days is impacted greatly. When the Dow has risen less than 30% over the 1000-day period (as is the case at present; N = 64), the next eighty days average a gain of only .69% (39 up, 25 down). When the Dow has risen more than 30% over the 1000-day period, the next eighty days average a gain of 3.32% (594 up, 231 down).
In general, the stronger the Dow's performance over the 1000-day period, the more favorable the outlook for the next 80 days. When the Dow makes a 1000 day high, but is up only modestly in that period, the next 80 days actually underperform the long-term historical norm.
Interestingly, however, when we look at how much the Dow has actually risen during the 1000 day period in which it made new price highs, the forecast for the next eighty days is impacted greatly. When the Dow has risen less than 30% over the 1000-day period (as is the case at present; N = 64), the next eighty days average a gain of only .69% (39 up, 25 down). When the Dow has risen more than 30% over the 1000-day period, the next eighty days average a gain of 3.32% (594 up, 231 down).
In general, the stronger the Dow's performance over the 1000-day period, the more favorable the outlook for the next 80 days. When the Dow makes a 1000 day high, but is up only modestly in that period, the next 80 days actually underperform the long-term historical norm.
Thursday, January 05, 2006
Three Strong Days in QQQQ: What Next?
The NASDAQ market (QQQQ) has been up approximately 3.74% in the past three days. Since January, 2003 (N = 756), we've had 62 occasions in which QQQQ has risen more than 3% in a three-day period. Three days later, the market is up by an average of .41% (41 up, 21 down), better than the average gain of .21% (407 up, 349 down) for the sample overall. Moreover, the strength following a strong three-day period tends to be greater when the prior three days have been up on above average volume. For example, when the market is up over 3% over a three-day period on above average volume (N = 31) based on a median split, the next three days are up by an average of .48% (22 up, 9 down). Note that Friday will be an unusual day due to the big unemployment number coming out in the morning, so generalizing from the past is more chancy than usual. Nonetheless, we've had solid strength on solid volume over three days and--all else being equal--that leads to residual strength over the next three days.
Wednesday, January 04, 2006
Up Day After a Strong Momentum Day
Tuesday was a strong day and, as our analysis suggested, Wednesday followed through to the upside. One notable aspect of Tuesday's strength was a very high Demand/Supply ratio, as mentioned on the Trading Psychology Weblog. I went back to January, 2003 in SPY (N = 749) and investigated occasions when the following occurred: 1) the market was up strong (> 1%) with a strong Demand reading (> 140) and 2) the following day was up. The 14 occasions that met these criteria (matching the current market) were up 6 times, down 8 the next day, for an average gain of .18%. Three days out, however, they were up 9 times, down 5 for an average gain of .66%. While this offers no directional edge to tomorrow's trade, it does suggest continued upside potential in the short run thereafter.
Tuesday, January 03, 2006
Strong Up Day: What Next?
We rose strongly on Tuesday after dipping well below the day's open. Since January, 2003 (N = 752), we've had 26 days where SPY has risen more than 1.5%. The next day, the market has been up 17 times, down 9 for an average gain of .15%. This compares favorably with the average daily gain of .05% (416 up, 336 down) for the sample overall. Strong days that occur after an initial move down below the day's open tend to carry the next day strength over to the next several days. Strong days that occur after a five day period of weakness and that occur on above average volume also tend to follow through better. For all these reasons, Tuesday's strength has set up expectations of strength for the remainder of the week. In fact, when the previous five days have been down more than1% and the most recent day is up more than 1.5% (N = 11), the next day is up 9 times, down twice for an average gain of .63%. This is an example of high strength tending to follow through in the short run--a pattern that sustained the upturn through Tuesday afternoon.
Monday, January 02, 2006
Using Market Delta in Trading
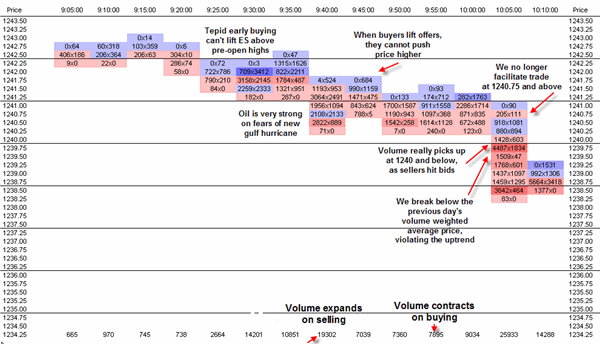
I've received a number of emails regarding the use of the Market Delta program in trading, so I decided to post here rather than answer the same questions separately.
For those not familiar with MD, it displays price in a bar chart but within the bar captures volume information. This includes total volume at each time and price and a division of the volume in terms of the number of contracts (or shares) traded at the bid price vs. the number traded at the offer. The chart above is taken from Market Delta; I have annotated it to show areas where you can see buying dry up and selling picking up. This is very helpful information for short-term traders.
The key is looking at the bars horizontally as well as vertically. When there's buying, for instance (buyers eager to get into the market and lifting offers), you can see increasing volume with higher price when you look vertically. You can also see increasing volume at each price relative to the previous bar when you look horizontally. Markets that are facilitating trade will show increasing horizontal and vertical volume. It's when volume peters out, both horizontally and vertically, that you start to look for short-term reversals.
When you combine the information from MD with the Market Profile, you can gain a very good understanding of the day's auction dynamics. You'll see volume pick up at range extremes prior to breakouts, and you'll see volume die out prior to mean reversions. Many good trade ideas can be developed from this combination of sources.
Another use for MD is looking at occasions when large traders are entering the market and seeing whether their big trades are predominantly at the bid or offer. Large traders will control market direction in the short-run; knowing whether they're leaning long or short is very useful information. Setting MD to a 1 tick reversal bar will basically show you every trade coming into the market and whether it's at bid or offer. Or you can just watch the shifts of volume within longer-term bars to see size coming in.
This article I wrote a while back explains why I think information re: large traders is important.
Several people have asked me about settings for bar coloration in MD. It's not crucial; just create a setting that gives you the darkest color (indicating highest selling or buying volumes) about a third of the time. That way, you'll know that volume is about 1 standard deviation above normal when you see the dark colors. Otherwise, color is much less important than the shifts of the numbers, vertically and horizontally.
Please note that I do not have a proprietary interest in MD, Market Profile, or any other programs I mention on my sites. I do keep my eyes open for unique implementations of trading software and try to bring this to readers' attention from time to time. Later this week I hope to talk with the founder of Ninja Trader and pass along some impressions of that program.
Hope this is helpful.
Sunday, January 01, 2006
Trading Psychology Announcement
I will resume the historical analyses of the market after Tuesday's trade. In the interim, check out my coming article in Trading Markets on turning around trading slumps and my recent and coming entries in the Trader Performance section of my personal site.
Subscribe to:
Posts (Atom)

 Posts


